HOW CAN WE HELP YOU?

Click to Call (Laredo) Click to Call (San Antonio)

201 W Del Mar Blvd, Suite 20
Laredo, TX 78041

Get Directions

3740 Colony Dr, Suite 280
San Antonio, TX 78230

Get Directions

AlphaSure Affordable Insurance Svcs Blog

The Hidden Costs of a Coverage Lapse in Car Insurance
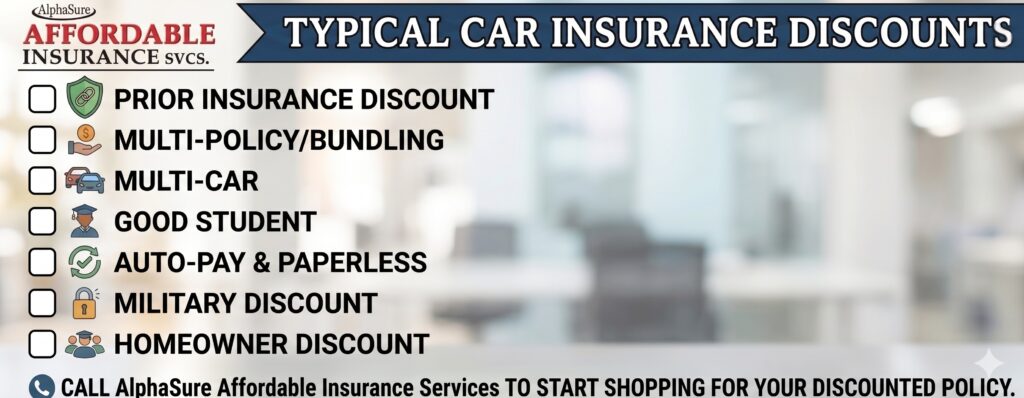
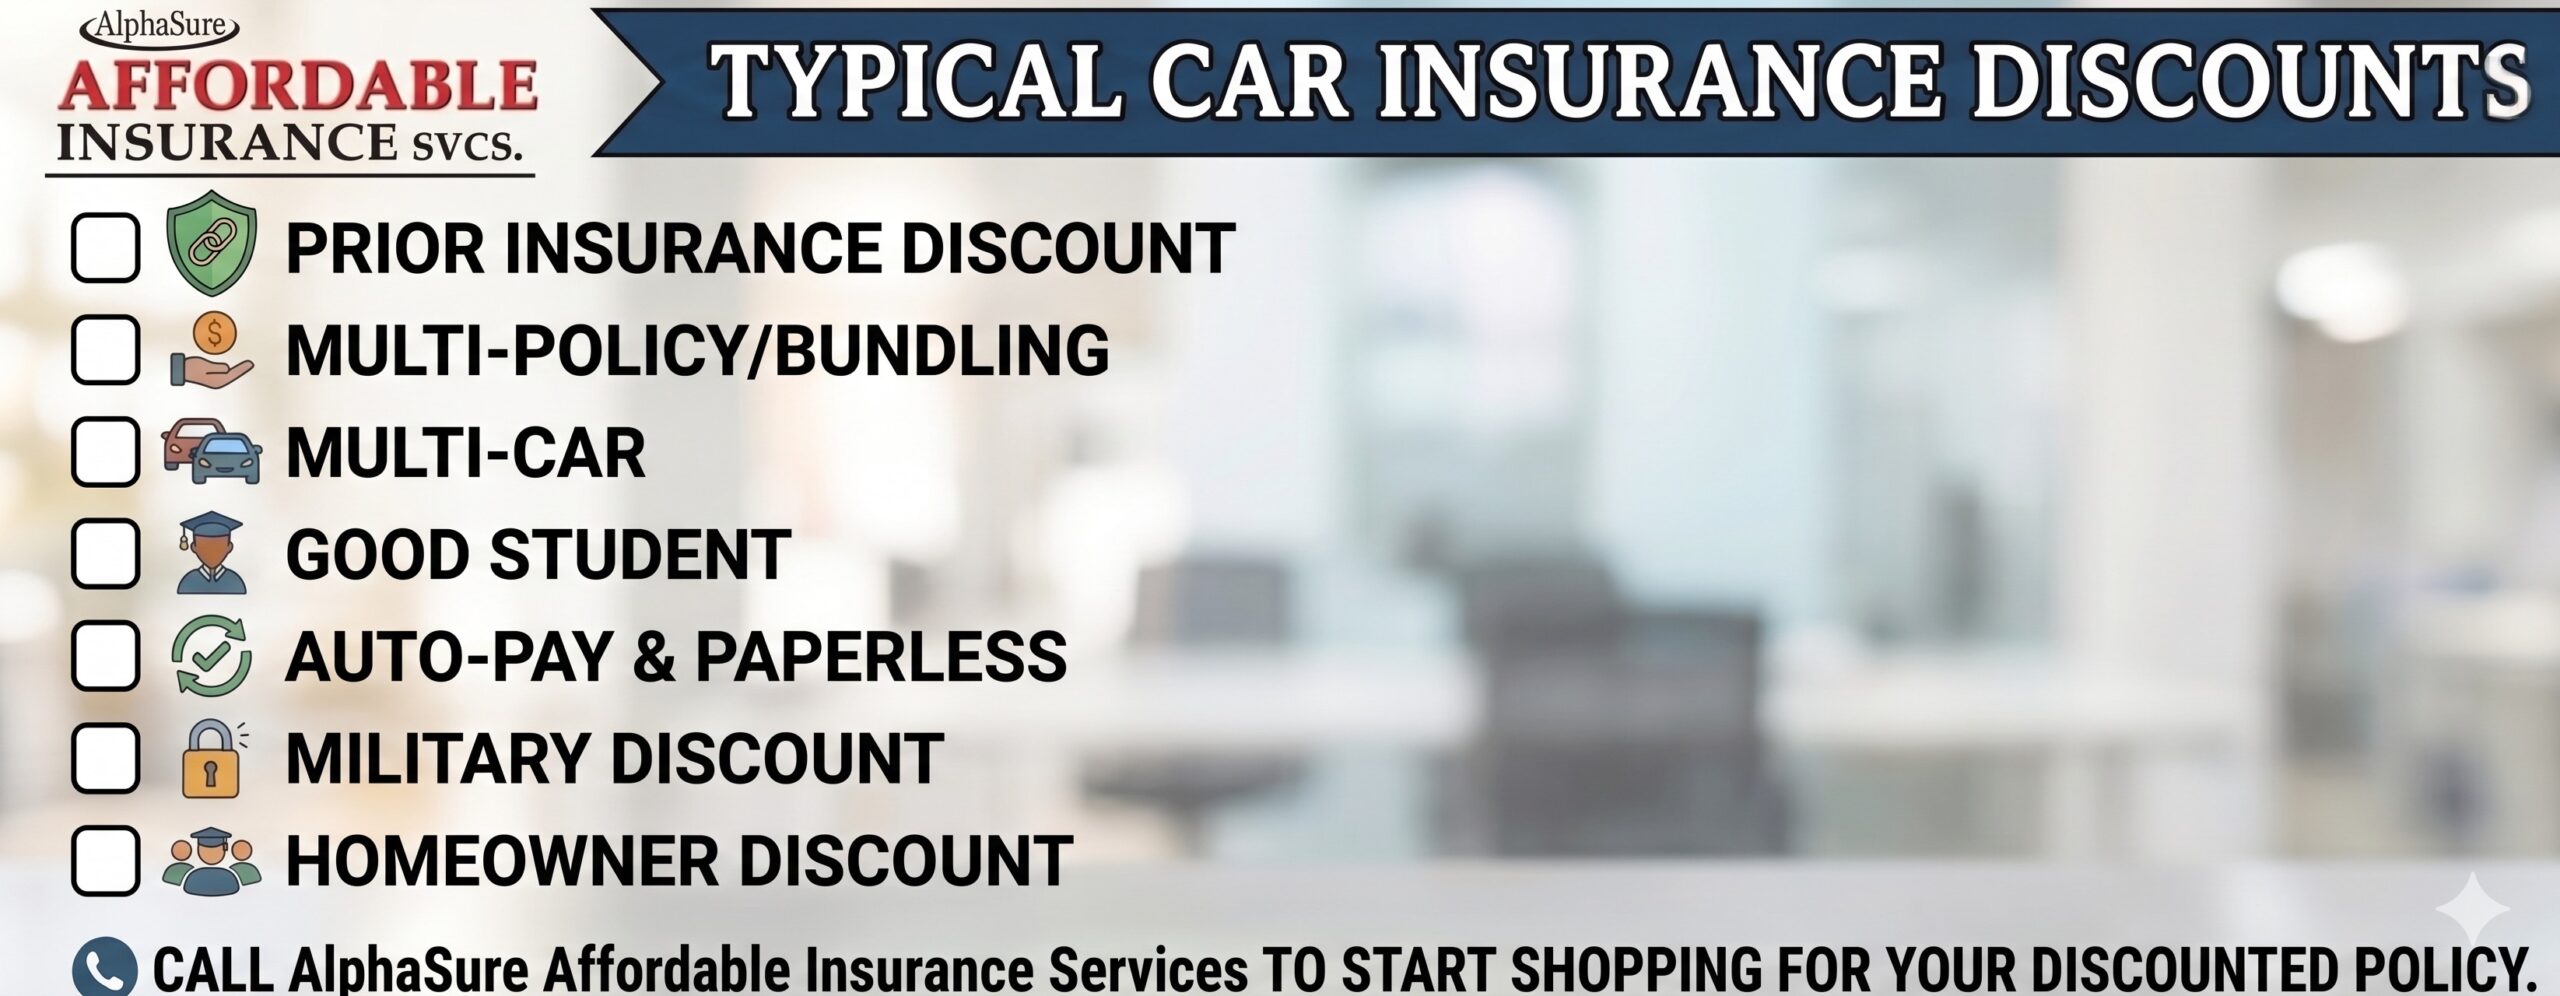
A checklist of typical discounts found in many Texas car insurance policies.

Have you ever thought about letting your car insurance coverage “pause” for a few weeks? Maybe you are between vehicles right now. Or perhaps you just want to save a quick buck this month. However, you should think twice before you make that choice.

A gap in your auto policy is called a coverage lapse. It might seem harmless at first glance, but it may cost you more in the long run. These unexpected costs can hurt your wallet for many years to come.

Fortunately, you can avoid these financial traps easily. Let us look at why keeping your policy active matters so much, and how an independent agency can protect your budget.

The Hidden Costs of a Car Insurance Coverage Lapse (And How to Avoid One)

The Real Price of a Car Insurance Gap

1. Your Premium Rates Will Increase

Insurance companies view drivers with a coverage gap as high-risk clients. Consequently, when you finally buy a new policy, companies will charge you a much higher premium. This is because, you will lose your “continuous insurance” discount. Thus, depending on the insurance company, a few days can double your future car insurance rates.

2. You Will Pay Heavy Legal Fines

In Texas, the TexasSure program keeps a database of insured vehicles. As a result, there some jurisdictions in Texas that actively seek to fine and tow uninsured vehicles. This will lead to fines and inconveniences that could have been avoided.

3. You Face High Out-of-Pocket Expenses

Accidents always happen when you least expect them. If you cause a crash during an insurance lapse, you must pay for all vehicle repairs out of your own pocket. Furthermore, you have to cover medical bills for anyone you may have injured. As a result, you can find yourself in a lawsuit. This single mistake can easily lead to complete financial ruin.

How to Safely Avoid a Car Insurance Coverage Lapse

You never have to suffer through these high costs. Instead, you can follow these simple steps to protect your household budget:

  • Use Non-Owner Car Insurance: If you sell your vehicle but plan to buy another one soon, get a non-owner policy. This special car insurance policy keeps your insurance history clean and keeps your future rates low.
  • Set Up Auto-Pay: Avoid accidental cancellations by letting your bank handle your monthly payments automatically.
  • Plan Your Timing Ahead: Never cancel an old policy until your new car insurance policy is active.

Let a Local Car Insurance Professional Do the Work

Shopping for car insurance coverage alone feels overwhelming. Fortunately, you do not have to do it by yourself. A local independent agent can find the best deals for your specific situation.

AlphaSure Affordable Insurance Services helps local drivers search the insurance market. Because they are independent, AlphaSure can compare multiple top companies at once. They work hard to find cheap car insurance or home insurance without sacrificing your protection.

Call a local independent insurance agent today to keep your record clean, avoid lapses, and save your hard-earned money.

Visit one of our Local Car Insurance Agencies

Call our Laredo, TX office at (956) 729-9500

Call our San Antonio, TX office at (210) 888-1750

Read More

Do You Have Low Liability Limits on Your Auto Insurance?

Person in a San Antonio Court litigating an at fault accident with low liability on his auto insurance

When you buy auto insurance in Texas, you might naturally focus on protecting your own vehicle. It makes perfect sense to worry about a dented bumper or a totaled car. However, many drivers make a major mistake during this process. They choose the lowest possible liability limits just to save a few dollars on their monthly premium bill.

Understanding Liability Coverage in Auto Insurance

What exactly is liability coverage? This crucial part of your auto insurance policy pays for property damage and bodily injuries you cause to other people in an accident. Currently, Texas law requires minimum limits of 30/60/25. This means that if you are at fault in an accident, your policy pays up to $30,000 for an injured person, $60,000 total for all injuries in one wreck, but not one person gets more than $30,000, and $25,000 for property damage.

These numbers might sound large at first, but medical care and new vehicles cost a fortune today. Consequently, if you cause a serious crash, you can easily blast past these minimum state requirements. For instance, if you total someone’s new $60,000 SUV, your minimum policy only covers $25,000. Therefore, you must pay the remaining $35,000 completely out of your own pocket.

The Real Danger Behind Having Low Liability Limits on an Auto Insurance Policy: Lawsuits and Legal Fees

Even worse, the other driver might decide to sue you for the remaining balance. A massive lawsuit brings expensive lawyers, courtroom costs, and endless stress. Ultimately, paying for a major legal battle is far worse than losing a cheap $2,500 car. If you lose the case, those mounting legal bills can drain your personal savings, spark wage garnishment, or force you to sell your assets.

Low liability limits put your entire financial future at risk simply to save a tiny bit of money today. Fortunately, increasing your coverage limits gives you peace of mind and shields your hard-earned money from sudden disasters.

Protect Yourself with a Local Car Insurance Expert

Do not navigate these complex choices alone. Call a local independent insurance agent like AlphaSure Affordable Insurance Services today. Independent agents compare multiple companies to find the best rates for your car or home insurance. They will ensure you get the protection you actually need at a price you can easily afford.

Read More

Rental Reimbursement & Car Insurance in Texas

Car insurance customer is picking up his rental car at a San Antonio rental car agency

Imagine this scenario: You just filed a collision claim  on your car insurance after a fender bender in downtown San Antonio. Your vehicle needs a week of bodywork, so you head to a local San Antonio rental car agency to pick up a temporary ride. You have a road trip planned down Interstate 35 to Laredo, but you stop and wonder: How does my Texas car insurance policy handle this rental?

Understanding how your policy moves with you is the best way to avoid surprise costs. Let’s break down how rental reimbursement works, whether it pays for physical damage, and if your coverage will follow you down to Laredo.

What is Rental Reimbursement Coverage in a Car Insurance Policy?

Rental reimbursement is an optional coverage add-on to your Texas auto insurance policy. You must buy this coverage before an accident occurs to use it. If your personal car is damaged in a covered collision or comprehensive claim, this feature pays for cost of a temporary rental car while your vehicle is in the shop.  It will pay up to the limits shown your policy declarations page.

Texas policies typically structure this benefit with a daily limit and a maximum total limit per accident. For example, your plan might cover up to $40 per day for a maximum of 30 days. The insurance company pays the rental agency directly, or they reimburse you after you submit your receipts.

However, you must remember one key detail: This coverage only pays the rental agency’s daily fee, taxes, and basic administrative costs. It does not pay for gasoline, security deposits, nor any damage you may cause to the rental.

Will Rental Reimbursement Cover Damages to the Rental Car?

No, rental reimbursement coverage will not pay for physical damage to the rental car. Rental reimbursement only pays the cost to rent the vehicle up the policy limits shown on the car insurance policy declarations.

If you scrape a pole or get into a second accident while driving the rental vehicle, rental reimbursement will not help. Instead, your primary auto policy may step in to cover those physical losses. Refer to your policy or talk to a licensed agent about this.

Will Your Car Insurance Follow You to Laredo?

First off, it is very important to read your policy or talk to your agent. In general, your auto insurance coverage may follow you. When you pick up your temporary vehicle in San Antonio and drive south to Laredo, your liability coverage to others will cover the damages you cause to another party. Some policies, but not all, will extend physical damage coverage, comprehensive and collision to rental car minus the deductible. 

For some car insurance policies, this information may not apply.

Nevertheless, here is how your primary car insurance policy may apply to that rental car:

  • Liability Coverage: If you cause an accident on the way to Laredo, the liability insurance portion of your auto policy will pay for the damage to the other driver’s car and any medical bills they incur.
  • Collision Coverage: If you hit a guardrail or another vehicle, your collision coverage pays for the physical damage to the rental car, minus your deductible. Once again, read your policy carefully. Some non-standard policies may not cover rental cars at all.
  • Comprehensive Coverage: If a sudden hailstorm damages the rental car while parked in Laredo, your comprehensive coverage will pay for the repairs, minus your deductible.

Watch Out for Rental Agency Fees

Your personal insurance policy may cover the physical damage of the rental, but rental car agencies often charge extra hidden fees after an accident. The two most common are “loss of use” fees and “diminution of value” fees.

Loss of use fees are assessed by the rental car company to cover the money the rental agency loses while their car is in the shop and cannot be rented to someone else. Diminution of value fee is assessed to cover the drop in the vehicle’s resale market value because it now has an accident history.

Standard Texas auto policies frequently do not pay for these rental car agency administrative fees. Because these fees are typically not covered by a car insurance policy, it is highly recommended to purchase a damage waiver directly from the rental car agency.

Let AlphaSure Affordable Insurance Services Find the Right Policy for You

Navigating the details of rental reimbursement coverage does not have to be complicated. When you are shopping for your next auto insurance policy, partnering with an independent insurance agency like AlphaSure Affordable Insurance Services gives you the advantage. Because we are independent, we work with multiple top-rated insurance carriers to find you the best coverage and rates for your specific needs. Whether you want to ensure your coverage follows you on your next road trip or you just need to update your existing policy, our local team is here to help. You can easily go online to request a quick quote, give us a call, or stop by to visit us in person at either of our convenient office locations in San Antonio or Laredo, Texas.

Read More

Buying a car? Consider the Cost of Car Insurance First

shopper purchasing a car and discussing the total cost including car insurance

Are you buying a new or used car in Texas? Many buyers only look at the dealership sticker price. However, you must look at the total cost of ownership. Your car insurance premium makes up a massive part of this total cost. If you ignore insurance rates, you might end up with a monthly bill you simply cannot afford.

Therefore, researching coverage costs is vital. When you insure a vehicle, the insurance company evaluates its make, model, and year. Furthermore, they look at repair costs, theft rates, and safety ratings.

Let us dive into which vehicles from 2006 to 2025 cost the most and least to cover in the Lone Star State.

The Least Expensive Vehicles to for Car Insurance (2006–2025)

Generally, family-friendly vehicles and small SUVs cost the least to protect. Why? Because drivers usually operate them safely. In addition, they feature excellent safety equipment and use cheap replacement parts.

Here are the cheapest types and models to insure:

  • Small and Midsize SUVs: The Honda CR-V, Subaru Outback, and Ford Escape consistently offer great rates. These cars protect passengers well in crashes.
  • Minivans: The Honda Odyssey and Chrysler Pacifica rank as some of the cheapest vehicles to insure. Families drive them carefully, which leads to fewer accidents.
  • Rugged Off-Roaders: The Jeep Wrangler is historically cheap to cover. Mechanics can easily find and replace its parts.

New vs. Used: Older models, like a 2010 Honda CR-V, will cost much less to insure than a brand-new 2025 model. Older cars typically do not have modern aged technical components, like sensors. Consequently, this lowers the to repair a small fender bender.

The Most Expensive Vehicles for Car Insurance (2006–2025)

On the flip side, luxury cars, sports cars, and high-end electric vehicles will drain your wallet. These vehicles cost a fortune to repair.

  • Luxury Sports Cars: The Maserati Quattroporte, Porsche 911, and Audi R8 top the charts every year. They require expensive, imported parts and specialized labor.
  • High-Performance Muscle Cars: The Dodge Charger SRT Hellcat and Ford Mustang Shelby are very costly. Insurance companies know that drivers push these fast cars to their limits, which causes more severe wrecks.
  • Premium Electric Vehicles (EVs): High-end EVs, like the Tesla Model S and Porsche Taycan, carry massive insurance tags. They feature expensive battery packs and complex computers. Furthermore, mechanics need special training to fix them.

Why Texas Drivers Pay More for Car Insurance

Texas drivers face unique challenges on the road. We deal with destructive hail storms, busy highways in cities like San Antonio and Laredo, and a high number of uninsured drivers. Because of these local risks, finding a car in a low insurance bracket is even more critical here than in other states.

Conclusion

Before you sign any paperwork at the dealership, call an independent insurance agent like AlphaSure Affordable Insurance Services for free car insurance quote. Give them the Vehicle Identification Number (VIN) of the specific car you want. Getting a quote first ensures your dream car does not become a financial nightmare.

Read More

Understanding Permissive Use in Texas Car Insurance

Person handing over keys to another person because the car insurance allows permissive use for non household members

Have you ever lent your car keys to a friend so they could run a quick errand? Or maybe you have a relative visiting from out of town who needs to use your truck. When someone else gets behind your wheel, you might wonder: will my car insurance cover me if they crash?

To answer this question simply, car insurance in Texas generally follows the vehicle rather than the driver. Consequently, this rule introduces an important concept known as permissive use coverage. Let’s break down exactly what this means, when it applies, and how it impacts the people living under your roof.

What Is Permissive Use Coverage in Car Insurance?

First of all, permissive use coverage is a standard feature in most Texas auto policies. Specifically, it extends your car insurance protection to someone who drives your vehicle with your explicit or implied permission. Because Texas insurance follows the car, your policy acts as the primary insurance if that driver gets into an accident.

As a result, your insurance company will help pay for damages and injuries up to your policy limits, just as if you were driving. Furthermore, the borrower’s personal auto insurance, if they have it, usually acts as secondary coverage. Therefore, their insurance will only handle extra costs if your limits completely run out.

When Does It Kick In?

In order for this protection to apply, permissive use coverage kicks in only when two specific conditions are met:

  1. You gave clear permission: First, the driver must have your consent to use the vehicle. This can be verbal, written, or implied by actions, such as handing over the keys.
  2. The use is occasional: Second, this coverage is strictly meant for rare or short-term situations. For example, a neighbor borrowing your truck to haul furniture or a friend driving you home when you feel unwell.

Do Household Members Benefit From This?

Surprisingly, the answer is generally no. Household members usually do not benefit from permissive use coverage.  It is an insurance company policy guideline that all household members must be listed and rated on your policy. If you fail to disclose or hide household members the car insurance application is fraudulent and coverage may be denied.

The reason for this is that insurance companies view permission differently when it comes to the people you live with. Because household members have constant access to your keys, insurers do not consider their driving to be “occasional.” Instead, insurance companies assume that anyone living in your home will drive your car regularly. For this reason, permissive use is typically reserved for people who live outside your household and do not keep your car at their place.

Do You Need to List Household Members on Your Car Insurance Policy?

Because of these rules, you must list all licensed household members on your car insurance policy.

Indeed, when you apply for or renew auto insurance in Texas, the company will ask you to disclose every licensed driver living at your address. This includes your spouse, your driving-age children, roommates, and extended family members. Subsequently, the insurance company uses this information to calculate your premium based on the total risk of everyone who has access to the vehicle.

However, if a household member has a terrible driving record and is driving your rates too high, you have an alternative option in Texas. You can sign a named driver exclusion. This form officially states that the specific person will not be covered if that person drives your car, with or without your permission. While it keeps your rates lower, it entirely removes them from your insurance plan.

What Happens If You Don’t List Household Members?

Ultimately, failing to list licensed household members can lead to severe financial consequences. If an unlisted household member drives your car and gets into an accident, your insurance company may take the following actions:

  • Deny the claim: First, the insurer can refuse to pay for any vehicle damage or medical bills. They will argue that you hid a regular driver, which violates your policy contract.
  • Cancel your policy: In addition, the company may cancel your insurance entirely due to material misrepresentation, which is a form of application fraud.
  • Leave you personally liable: Finally, if the claim is denied, you and the driver could be sued personally for all injuries and property damage caused by the accident.

In conclusion, to protect your finances and your family, always keep your insurance company informed. By adding every licensed resident to your policy, you can hit the Texas roads with total peace of mind.

Another Exception: Named Driver Car Insurance Policies

When exploring this topic, you might wonder about cheaper policy types, such as “named driver” policies. Historically, a named driver policy provided auto coverage only to the specific individuals listed as rated drivers on the policy declarations page. Consequently, these rigid plans do not cover permissive use at all. If an unlisted household member or friend drove the car—even with your explicit permission—any accident claim would be instantly denied.

Because these policies left so many drivers unprotected, the state took strict action. Specifically, Texas passed House Bill 259, which officially banned insurance companies from issuing or renewing named driver policies. As a result, standard policies are now the norm, ensuring better baseline protection for Texas drivers. Check your policy and ask your agent if you have a named driver policy.

Call an Independent Insurance Agent for Guidance

An independent insurance agent, like AlphaSure Affordable Insurance Services, can not only shop around for the best car insurance deal for you, but also guide you in learning more about coverage gaps as it relates to household members or vehicle usage. Be sure to be completely honest with your agent so that he can guide you in the right direction.

Call today for a quote or visit us at our one of our local offices or go online.

Read More

Auto Insurance, Teens, and Roommates-Texas Policies

Texas Teen away from home without a car and no auto insurance

As your children grow up and move out, your role as a parent changes, but your desire to protect them remains the same. If your teen is currently living away from home with roommates and does not own a vehicle, you might think you can safely remove them from your auto insurance policy. However, Texas insurance rules can be tricky. Failing to understand how household residents affect your coverage could leave you or your child vulnerable to massive financial risks.

Before you make any changes to your policy, you must know how Texas law and insurance companies view your teen’s new living situation.

Auto Insurance -The Resident Relative Rule in Texas

In the Lone Star State, standard auto insurance policies typically require you to list all licensed drivers living in your household. Insurance providers calculate your premiums based on the risk of everyone who has regular access to your vehicles.

When your teen moves out to live with roommates, their status depends heavily on whether the move is temporary or permanent. If your teen is away at college in Laredo or San Antonio but returns home during breaks, insurance companies usually still consider your primary residence as their permanent home. In this scenario, you must keep them on your policy. Ask your auto insurance agent about a discount for teens away from home without a car.

The Risk of Roommates and Borrowed Cars

What if your teen is completely independent, lives with roommates, and doesn’t have a car? You might assume they do not need auto insurance at all. However, living with roommates introduces a unique risk: shared access to vehicles.

If your teen occasionally borrows a roommate’s car to run an errand, permissive use coverage might apply. Permissive use means the vehicle owner’s insurance covers an occasional driver in an accident. Unfortunately, insurance companies strictly define “occasional.” If your teen drives a roommate’s car regularly, the roommate’s insurance company may deny a claim after an accident because your teen is an unlisted household resident. Worse yet, if the household resident is not disclosed to the roommate’s auto policy, a claim may be denied. Talk to your agent about this possible gap in coverage.

If your teen causes an accident while driving an uninsured or underinsured vehicle, they could face personal lawsuits. Although it won’t protect the physical damage to the roommate’s car, keeping your teen on your policy or securing a non-owner car insurance policy ensures they always carry liability protection, no matter whose car they drive.

Should You Keep Your Teen Listed on your Auto Insurance Policy?

Maintaining continuous car insurance history is incredibly valuable for young drivers. This is because the continuous prior insurance discount is one of the biggest discounts available for auto insurance policies. If you remove your teen from your policy now, they will show a gap in coverage when they eventually buy a vehicle and their own policy. Thus, your teen will not qualify for the prior insurance discount.

Additionally, keeping your teen on your auto insurance policy protects them as a passenger or a pedestrian. If a reckless driver hits your teen while they are walking across a street in downtown San Antonio, your policy’s Medical Payments or Personal Injury Protection (PIP) can help cover their medical bills.

Consult a Local Independent Auto Insurance Agent

Because every family and living situation is unique, you should not guess when it comes to your insurance coverage. Working with a local independent insurance agent allows you to explore multiple insurance carriers to find the best rates.

An independent agency like AlphaSure Affordable Insurance Services can evaluate your current policy and provide advice regarding your teen’s specific living arrangements. Whether your child is studying hard at a Texas A&M International University in Laredo or starting their first job with roommates, a local agent will help guide you when shopping for auto insurance.

Do you want to make sure your family has the right coverage? Contact AlphaSure Affordable Insurance Services today to speak with a professional and receive a personalized car insurance quote.

  • Call the Laredo, TX office at (956) 729-9500 or visit us at our local office.
  • Call the San Antonio, TX office at (210) 888-1750 or visit us at our local office.

AlphaSure Affordable Insurance Services is licensed to sell and service insurance policies in the Great State of Texas.

Read More

Why Car Insurance Rates Are Up

husband and wife discussing car insurance and other monthly bills at a dinner table

Why Car Insurance Rates Are Up: The Hidden Inflation Factors

If you have been shopping for car insurance recently, you have likely experienced sticker shock. Since 2020, national motor vehicle insurance rates have risen by approximately 53.7%, vastly outpacing general economic inflation.

While it is easy to assume that higher costs are just random rate hikes, the reality is a complex mix of economic pressures.

Here are the four primary factors inflating your car insurance premiums today.

1. Car Insurance, Economic Inflation and the Price of Oil

It is a common misconception that high gas prices reduce driving enough to significantly lower auto insurance rates. Instead, the real impact of the oil and gas industry on your car insurance is found in the supply chain.

Modern vehicle components—such as bumper covers and headlight housings—are predominantly manufactured using plastics derived from crude oil. When global energy markets experience volatility and oil prices spike, the cost of raw plastic resins increases rapidly. These inflated material costs are passed down to local auto body shops, meaning that car insurance companies must pay out larger settlements for basic physical damage and collision claims.

2. Advanced Technology and the Cost of “Fender Benders”

Cars are safer than ever, but that safety comes with a steep price tag. Many of today’s vehicles are equipped with Advanced Driver Assistance Systems (ADAS), which include blind-spot monitors, backup cameras, and automatic emergency braking.

Historically, a minor fender bender resulted in a cheap, cosmetic bumper replacement. Today, a minor low-speed collision can destroy sensitive, highly calibrated electronic sensors. Research from the American Automobile Association (AAA) shows that the presence of ADAS components can add up to 37.6% to the total repair cost following a crash. The average cost to replace ADAS components in a minor front-end collision is now $1,540, permanently raising the baseline severity of claims.

3. Extreme Weather and Natural Disasters

Your vehicle doesn’t even have to be moving to suffer a total loss. Catastrophic weather events have increasingly disrupted the property and casualty insurance markets, and auto insurance is feeling the impact.

Natural disasters generate massive volumes of unusually expensive claims all at once. For example, hurricanes in Florida in 2024 resulted in over 100,000 auto insurance claims, while severe midwestern hailstorms account for roughly 12% of all comprehensive car insurance claims nationwide. As insurers pay out billions for these localized weather events, global reinsurance costs rise, and the financial ripple effect is felt in premiums across the country.

4. Social Inflation and Legal System Abuse

While the cost of plastic parts and microchips is driven by economic inflation, the liability portion of your premium is heavily impacted by “social inflation”. This term refers to the rising costs of insurance claims driven by societal trends, third-party litigation funding, and aggressive “billboard attorney” advertising.

When minor accidents are escalated into drawn-out, frivolous lawsuits resulting in large jury verdicts, the entire insurance pool absorbs the blow. Between 2014 and 2023, social and economic inflation drove auto liability losses and defense containment costs up by an estimated $118.9 billion to $137.2 billion. This legal system abuse acts as a hidden tax on consumers, raising premiums regardless of your personal driving record.

Shop for Car Insurance with AlphaSure Affordable Insurance Services

Navigating rising premiums can be frustrating, but you don’t have to do it alone. AlphaSure Affordable Insurance Services is a trusted independent insurance agency proudly licensed in Texas. Because we represent several top-rated insurance companies, we can shop the market on your behalf to find the most cost-effective coverage for your insurance needs.

Whether you need personal auto insurance coverage or commercial trucking insurance, we are here to help. We offer free consultations with 100% customer satisfaction in mind.

Contact us today at one of our convenient Texas locations:

Read More

Understanding Car Insurance Policy Limits: A Guide for Texas Drivers

Person driving with car insurance downtown San Antonio TX

When shopping for auto coverage, it’s easy to focus solely on the monthly premium. However, the most critical part of your plan—the part that protects your financial future—is the car insurance policy limits. At AlphaSure Affordable Insurance Services, we believe that being informed is the first step toward being protected.

As an independent insurance agent serving both San Antonio, TX and Laredo, TX, I see firsthand how policy limits can make or break a family’s finances after an accident. Consequently, whether you are commuting on I-35 or navigating the busy streets of downtown Laredo, understanding what your policy covers is essential.

What are Car Insurance Policy Limits?

Simply put, a policy limit is the maximum amount an insurance company will pay for a covered claim. In Texas, drivers are required to carry a minimum amount of liability coverage, often referred to as 30/60/25 coverage.

  • $30,000 for bodily injury per person.
  • $60,000 for total bodily injury per accident.
  • $25,000 for property damage per accident.

While these are the legal minimums, they are often insufficient for serious accidents. For instance, if the damages exceed these limits, you could be held personally liable for the remaining balance.

Why Local Expertise Matters

Choosing the right limits requires a balance between affordability and adequate protection. In addition to basic coverage needs, residents in San Antonio and Laredo face unique driving conditions, from heavy commercial traffic to unpredictable weather. Therefore, an independent insurance agent can compare multiple carriers to find high-limit policies that still fit your budget, ensuring you aren’t left vulnerable.

FAQs About Car Insurance Policy Limits

1. What happens if a claim exceeds my policy limits? If the cost of repairs or medical bills is higher than your limit, the insurance company will only pay up to that maximum. As a result, you are legally responsible for the “out-of-pocket” difference, which could lead to lawsuits or wage garnishment.

2. Is the Texas state minimum coverage enough? Generally speaking, no. With the rising costs of medical care and modern vehicle repairs, a $25,000 property damage limit can be exhausted quickly. Specifically, this occurs if multiple vehicles are involved or if you hit a high-end SUV.

3. How much do higher limits cost? Surprisingly, increasing your limits from the state minimum to a more robust 100/300/100 plan is often more affordable than people realize. Because we work with various providers, we can shop around to find the best rate for higher protection.

4. Can I have different limits for different cars? Yes, though it is often simpler and more cost-effective to have consistent limits across a multi-car policy. Ultimately, we can help you evaluate the value of each vehicle to determine the best strategy.

Ready to Review Your Coverage?

In conclusion, don’t wait until after an accident to find out your limits are too low. As your local independent insurance agent, AlphaSure is here to help you navigate the complexities of Texas insurance laws.

Contact AlphaSure Affordable Insurance Services today for a comprehensive policy review in San Antonio or Laredo!

Local Contact Information

AlphaSure Affordable Insurance Services Serving San Antonio, Laredo, and all of South Texas.

  • In Laredo, Texas call: (956) 729-9500
  • In San Antonio, Texas call: (210) 888-1750
  • Check out our website for more information

Read More

Can I Add My Teen Driver to My Auto Insurance?

What to Know About Teen Auto Insurance in Texas

When your teen is ready to drive in San Antonio, TX, it is important to make sure they are properly covered under your auto insurance policy. Texas has specific requirements for teen drivers, and insurance needs vary depending on whether your teen has a learner’s permit or a full driver’s license. The agents at AlphaSure Affordable Insurance Services can help guide you through the process and ensure your family meets all state requirements.

How Teen Drivers Affect Your Auto Insurance Policy

Teen Drivers With a Learner’s Permit

Teens between the ages of 15 and 17 may obtain a learner’s permit in Texas. Once your teen has a permit and access to your vehicle, it is important to notify your insurance provider. While permit holders are typically required to drive with a licensed adult at least 21 years old, they must still be covered by an auto insurance policy.

If a teen with a learner’s permit is involved in an accident while driving without the required supervision, claims may be denied, and parents or guardians could be held financially responsible. Texas law requires all drivers to meet minimum liability insurance limits, regardless of the type of license held.

Teen Drivers With a Full License

Once a teen obtains a full, unrestricted Texas driver’s license, they must be added to the auto insurance policy immediately and before driving independently. Licensed teen drivers are considered regular operators of the vehicle and are rated accordingly under the policy.

Teens who are 18 years or older must still meet all licensing requirements and maintain valid auto insurance coverage. Driving without proper insurance can result in fines, license suspension, and financial liability.

Contact AlphaSure Affordable Insurance Services

At AlphaSure Affordable Insurance Services, we help families in San Antonio, TX make sure teen drivers are properly insured and compliant with Texas insurance laws. Contact our team today to review your policy, discuss coverage options, and ensure every driver in your household is protected.

Read More

Navigating Car Insurance for Teen Drivers in South Texas

A young woman wearing a UTSA shirt drives a car through the streets of downtown San Antonio, Texas, near landmarks like the Aztec Theatre and Tower of the Americas. Local residents often look for affordable car insurance for a teen driver in San Antonio and Laredo, TX

Watching your teenager pull out of the driveway for the first time is a major milestone, and let’s be honest, a bit of a nerve-wracking one. Beyond the safety concerns, many parents in San Antonio and Laredo find themselves bracing for the “teen driver tax” on their monthly car insurance premiums.

At AlphaSure Affordable Insurance Services, we know that finding affordable car insurance for a teen driver can feel like an uphill battle. However, as an independent insurance agent, we have a unique advantage: we work for several insurance companies not just one! Thus, we compare rates across multiple carriers to find the best car insurance for your budget.

Why Is Teen Car Insurance Higher in San Antonio and Laredo?

Texas is a big state with busy roads. Whether your teen is navigating the Loop 1604 in San Antonio or driving near the border in Laredo, TX, the risks are statistically higher for inexperienced drivers. Moreover, insurance companies base their rates on “risk,” and unfortunately, drivers aged 16–19 are categorized in the highest risk bracket due to a lack of driving history.

However, don’t panic there are ways to bring those costs down without sacrificing coverage.


FAQs: What Increases or Decreases My Car Insurance Premium?

What will increase my teen’s insurance premium?

  • High-Performance Vehicles: Putting a 17-year-old behind the wheel of a sports car or a brand-new luxury SUV will skyrocket your rates. On the other hand, and old vehicle with liability only will save you money.
  • Traffic Violations: A single speeding ticket or at-fault accident can lead to significant surcharges for several years.
  • Minimum Coverage Limits: While it might seem cheaper to get the bare minimum required by Texas law, if your teen is in a multi-car accident, you could end up paying thousands out of pocket. Higher risk often leads to higher long-term costs.

What will decrease my teen’s insurance premium?

  • The “Good Student” Discount: Most carriers offer a discount (sometimes up to 10–15%) for students who maintain a “B” average or higher.
  • Driver’s Ed Completion: Completing a state-approved driver education course isn’t just about getting a license. Some companies offer Drivers Ed Discount. Call us for more information.
  • The “Resident Student” Rule: If your teen is headed off to college (like UTSA or TAMIU) and stays more than 100 miles away without a car, you may qualify for a significant discount.
  • Telematics Programs: Many of our carriers offer “plug-in” or app-based programs that track driving habits. Safe driving equals lower rates.

The Value of an Independent Insurance Agent

Why call ten different companies when you can make one call to AlphaSure Affordable Insurance Svs?

As an independent insurance agent serving both San Antonio and Laredo, TX we understand the local market. In addition, we will try to bundle your home and auto policies, apply multi-car discounts, and pivot between carriers if your current one raises rates unexpectedly at renewal.

Ready to get a car insurance quote?

Don’t let the cost of a new driver stall your family’s plans. Contact AlphaSure Affordable Insurance Services today for a free, no-obligation quote.

Read More