HOW CAN WE HELP YOU?

Click to Call (Laredo) Click to Call (San Antonio)

201 W Del Mar Blvd, Suite 20
Laredo, TX 78041

Get Directions

3740 Colony Dr, Suite 280
San Antonio, TX 78230

Get Directions

AlphaSure Affordable Insurance Svcs Blog

Car Insurance Premium Impact: Car Crash Data San Antonio vs Laredo

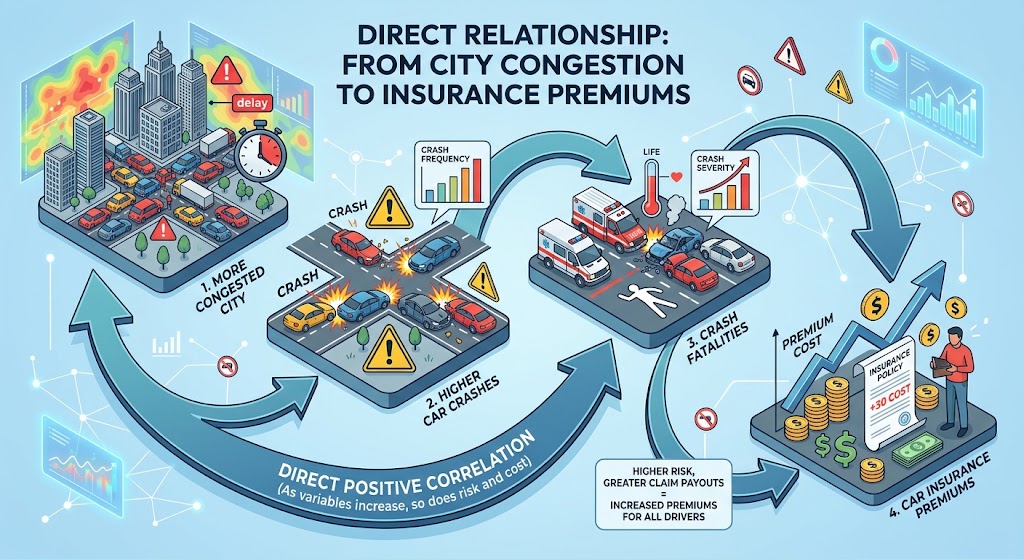
Car insurance diagram depicting the relationship between frequent car crashes and higher insurance premiums

Texas is a massive state. Because of its incredible size, Texans drive everywhere. Whether you commute to work daily or take weekend road trips, you spend a lot of time behind the wheel. Sadly, more time on the road means a higher risk of accidents. If you live in a busy Texas city, you need good car insurance to protect your family and your wallet.

Today, we will compare car crash statistics between two major Texas cities: San Antonio and Laredo. We will also explore how these numbers impact your local roads and why proper coverage matters so much.

The Raw Numbers: San Antonio vs. Laredo

When you look at the crash data, you see a massive difference between San Antonio and Laredo. The Texas Department of Transportation (TxDOT) is the state agency that tracks these crash numbers every year. In 2024, according to the Texas Department of Transportation, the state recorded thousands of wrecks in both regions. However, San Antonio saw far more accidents than Laredo.

Metric (2024 TxDOT Data)San AntonioLaredo
Total Crashes39,8056,512
Fatal Crashes16218
Total Fatalities17018

As the table shows, San Antonio reported roughly 39,800 total crashes. On the other hand, Laredo reported roughly 6,500 crashes. Therefore, San Antonio experiences about six times as many car accidents as Laredo.

This difference makes sense when you compare their populations. San Antonio has nearly 1.5 million residents. Meanwhile, Laredo has around 250,000 residents. More people naturally lead to more crowded roads, heavy congestion, and more frequent fender benders.

Diving Deeper: Impact on Car Insurance by San Antonio’s Congested Highways

San Antonio is a sprawling urban center. It features a complex network of major highways. Interstates like I-10, I-35, and freeways like Loop 1604 carry millions of cars every single week. Because of this heavy traffic, drivers face extreme congestion during morning and evening rush hours. Frustrated drivers often speed, change lanes aggressively, or follow other cars too closely.

Furthermore, according to the US Census, San Antonio was the fourth fastest growing city in 2024 and grows larger every day. New residents move to the city constantly. This rapid growth puts a heavy strain on the local infrastructure. Construction zones pop up everywhere, which confuses drivers and leads to unexpected sudden stops. Consequently, the high crash volume directly influences how insurers calculate car insurance premiums. According to Fred Gonzalez, a 25 year veteran of the insurance industry states, “indeed, ever since I’ve worked in the insurance business, premiums in bigger cities are much higher than if you lived in a smaller city.” Moreover, he states, “car insurance companies have made their pricing models very elaborate and moving from one zip code to another, even if it’s within the same city, may cause a change in premium, up or down.” If you live in an area with a high crash rate, you might pay more for your auto policy because the risk is higher.

Diving Deeper: Laredo’s Heavy Commercial Traffic

Laredo tells a very different story. While it lacks the massive population of San Antonio, it holds a unique title. Laredo operates as the busiest inland port in the United States. Every day, thousands of 18-wheelers and commercial trucks cross the border. They transport billions of dollars in commercial goods. According to the Bureau of Transportation Statistics Laredo saw 12,882,715 trucks cross the border in 2023.

Because of this booming trade industry, Laredo drivers share the road with massive semi-trucks daily. An accident involving a standard passenger vehicle and a large commercial truck often results in heavy physical damage. While Laredo has fewer total crashes, the constant presence of heavy trucks makes driving risky in a different way. Truck drivers deal with huge blind spots and long stopping distances. If you drive a small sedan in Laredo, you need good car insurance policy to cover potential damages from an 18-wheeler collision.

The Financial Impact: Understanding Liability Payouts

After a crash, someone has to pay for the medical bills and the damaged property. This is where auto liability coverage steps in. Insurance companies do not publicly share the exact total sums they pay out in specific cities. However, we know that they pay millions of dollars every single year.

In Texas, state law requires the at-fault driver to pay for the damages. When a driver causes a wreck in San Antonio, their car insurance pays the victim. Because San Antonio has almost 40,000 crashes a year, insurance companies process a massive number of claims there. Legal data shows that the average litigated auto accident settlement in San Antonio hovers around $90,000. In Laredo, standard accident settlements sit slightly lower, averaging closer to the state median of $65,000 to $75,000. However, Laredo’s commercial truck accidents can trigger massive payouts because commercial policies carry much higher limits.

State Minimums vs. Real Protection

Every driver in Texas must carry a minimum amount of car insurance. The state requires a basic 30/60/25 liability policy. This means your insurance pays up to $30,000 for injuries per person, $60,000 for total injuries per crash, and $25,000 for property damage.

However, these minimum limits often fail to cover modern medical costs and repair bills. Think about it carefully. If you total someone’s brand-new luxury SUV in San Antonio, $25,000 will not replace that vehicle. If you cause a severe crash in Laredo, $30,000 will not cover a week in the hospital. If your policy limits run out, the victims can sue you personally for the rest of the money. Therefore, you should always buy more coverage than the state requires. Indeed, according to Fred Gonzalez, “liability is probably the most important part of a car insurance policy.” Thus to be well protected, you need a robust policy to shield your financial future.

How AlphaSure Affordable Insurance Services Can Help with Car Insurance

Shopping for the right car insurance feels overwhelming. Many people just go online and buy the cheapest policy they can find quickly. This mistake can cost you dearly after a bad accident. Instead of guessing, you should work with a local independent insurance agent like AlphaSure Affordable Insurance Services.

Unlike big-name captive companies that only sell one single brand, AlphaSure Affordable Insurance Services partners with multiple carriers. They do the hard work for you. Their agents will compare rates from different companies to find you the coverage you are seeking and at the most affordable price. Because they live and work in the area, they understand the local risks.

In addition to auto policies, AlphaSure Affordable Insurance Services can help you bundle your coverage. You can save a lot of money by buying your car insurance and your home insurance together with the same carrier. A trusted independent agent will review your current home insurance and give you options so you can make an informed decision. Thus, you will have peace of mind knowing you have gone over the options available to you so you can make the best decision.

Conclusion

Driving in Texas always carries some risk. San Antonio deals with intense urban traffic and a very high volume of crashes. Laredo faces the unique challenge of heavy commercial truck traffic. Both cities present clear, distinct risks on the road.

To stay safe, always practice defensive driving. Put away your cell phone, obey the speed limit, and watch out for large trucks. Most importantly, review your car insurance policy today. Call a local expert like AlphaSure Affordable Insurance Services. Let them evaluate your car insurance and home insurance limits. With the right team on your side, you can hit the Texas highways safely and confidently.
Read More

Two Car Insurance Policies in Texas: Who Pays First?

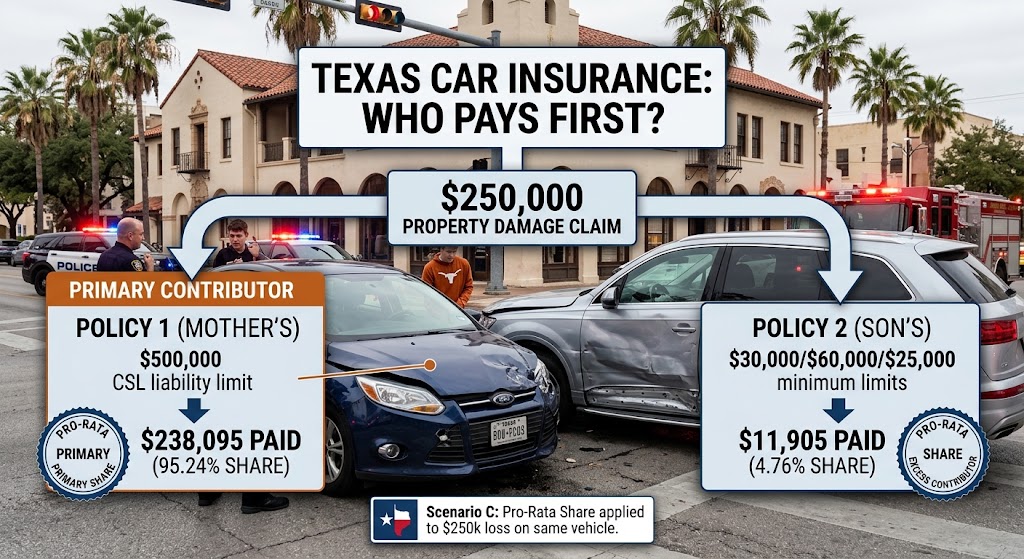
Car Insurance Diagram Depicting Who Pays First When there are two auto insurance policies on one car

Have you ever wondered what happens if two different car insurance policies cover the exact same vehicle? This situation happens more often than you might think. Maybe you bought a new policy and simply forgot to cancel your old one. Perhaps two different family members bought separate coverage for a shared family vehicle. Sometimes, people mistakenly think that doubling up on policies will give them double the protection.

No matter how the situation happens, double coverage creates a massive headache if an accident occurs. In the great state of Texas, the law provides clear rules to decide which insurance company must pay first. Today, we will explore these important rules. We will break down exactly how claims work when two policies clash. Furthermore, we will explain the math behind shared claims. Finally, we will show you how to untangle this mess and find the right coverage with a trusted local agent.

The Golden Rule: Car Insurance Follows the Auto

First, you need to understand the absolute golden rule of auto coverage. In Texas, car insurance follows the vehicle, not the driver.

What does this rule actually mean for you? It means the policy attached directly to the car will almost always pay first. Insurance experts call this main coverage the “primary” policy.

For example, imagine you let a good friend borrow your truck to move some furniture. While driving your truck, your friend runs a red light and causes a bad wreck. Because the insurance follows the vehicle, your insurance policy pays the victim’s bills first. Your friend’s personal insurance policy acts as a backup.

Industry professionals call this backup coverage the “secondary” or “excess” policy. The secondary policy only steps in if the crash damage costs more than your primary policy limits. Therefore, you always want to know whose name sits on the car title. Legal ownership heavily drives the entire claims process. When you know who owns the car, you usually know who pays first.

A Real-Life Scenario: The College Student

Let us look at a specific, real-life scenario to make these rules easy to understand. We can explore what happens when family members create accidental double coverage.

Imagine a family living in Laredo, Texas. The mother owns a reliable sedan and buys a car insurance policy to protect it. Her policy has a $500,000 Combined Single Limit (CSL) for liability. This generous limit means her policy can pay up to half a million dollars for any combination of bodily injuries and property damage caused by a crash.

Next, her son packs up his belongings and takes that exact sedan to college. While living away at school, the son decides he wants his own insurance. He buys a basic car insurance policy with the minimum limits required by Texas law. These state minimums provide $30,000 for bodily injury per person, $60,000 for bodily injury per accident, and $25,000 for property damage.

However, the mother forgets to cancel her large $500,000 policy. Now, two active policies cover the exact same vehicle at the exact same time.

Suddenly, disaster strikes. The son drives to the store and causes a massive accident on the highway. He hits a luxury sports car and causes a staggering $250,000 in property damage. When the victim files a claim, the insurance adjusters discover both active policies.

Which car insurance policy pays for this massive bill? How much money does each company pay? The answer depends entirely on one specific detail: who legally holds the title to the car.

Scenario A: The Mother Still Owns the Car

In most family situations, parents simply hand the car keys to their kids. They do not officially transfer the title at the Department of Motor Vehicles. If the mother still legally owns the car in this scenario, her large policy takes the primary spot.

Why does her policy pay first? Because her car insurance policy covers an “owned” vehicle. Standard insurance rules clearly state that any coverage for a non-owned vehicle acts strictly as a backup. Since the son does not legally own the sedan, his new policy serves only as excess coverage.

In this specific situation, the mother’s policy pays the entire $250,000 claim. Her large $500,000 limit easily covers the total property damage. Because her policy handles the whole bill, the son’s primary limits never trigger. His insurance company pays absolutely zero dollars. Consequently, the mother’s insurance rates will likely increase significantly upon her next renewal.

Scenario B: The Mother Transferred the Title

Now, let us flip the story to see a different outcome. Suppose the mother officially signed the vehicle title over to her son before he left for college. He legally owns the car now. However, the mother simply forgot to call her agent and cancel her old policy.

Because the son legally owns the car, his minimum-limit policy will now become the primary car insurance. The mother no longer has a true “insurable interest” in the vehicle because she officially gave it away. Therefore, her old policy now acts as the backup.

As a result, the son’s insurance company steps up to the plate first. They pay their absolute maximum property damage limit, which is only $25,000. This small payment leaves a massive $225,000 unpaid balance.

At this critical point, the mother’s $500,000 backup policy kicks into action. Her insurance company pays the remaining $225,000 to satisfy the victim’s claim. Both companies work together, but they pay based strictly on who owned the vehicle.

Scenario C: The Pro-Rata Share

Sometimes, insurance situations get extremely messy and complicated. What if the mother kept the title, but the son managed to list the car as an “owned” vehicle on his new policy? If both insurance companies investigate the claim and accept their policies as primary, Texas law uses a special “pro-rata” rule.

Pro-rata means the two insurance companies will share the final bill. They split the total cost based on the size of their individual coverage limits. They do not split the bill exactly in half. Instead, the company with the bigger policy pays a much bigger piece of the pie.

Let us do the exact math for this scenario. The mother has a $500,000 limit for property damage. The son has a $25,000 limit for property damage. Together, they bring $525,000 in total available coverage to the table.

To find the mother’s share, we divide her $500,000 limit by the $525,000 total. This calculation shows she holds about 95% of the total coverage. Therefore, her car insurance company pays 95% of the $250,000 crash. Her company will write a check for exactly $238,095.

Next, we look at the son. He holds the remaining 5% of the total coverage. His company will pay 5% of the crash, or roughly $11,905. Both insurers coordinate their payments to ensure they cover the victim completely without ever double-paying for the same damage.

Why Double Car Insurance Coverage Hurts You

Reading about these various scenarios might make double coverage sound like a great safety net. However, you should never carry two primary policies on one car on purpose. Doing so hurts you in several major ways.

First, you waste your hard-earned money. You pay two expensive premiums every single month for overlapping coverage that you cannot fully use. You cannot legally collect double the money for a single claim. Insurance laws strictly forbid you from profiting from an auto accident. The principle of indemnity says you can only restore what you lost.

Second, double coverage creates an absolute nightmare during the claims process. When two companies discover each other, they almost always argue over who pays first. This intense arguing delays your payout. You might wait weeks or even months for the companies to settle their legal dispute.

Meanwhile, the accident victim might decide to sue you personally because they grow tired of waiting. You want your car insurance claims handled quickly and smoothly. Double coverage may lead to a slow and stressful experience.

How a Local Independent Car Insurance Agent Can Help

You can easily avoid these expensive mistakes by working closely with a trusted professional. You should never guess when it comes to policy contracts and liability limits. Instead, you need an experienced guide to protect you.

This is exactly where a local independent insurance agent like AlphaSure Affordable Insurance Services steps in to help you. Unlike captive agents who only sell one single brand, independent agents are contracted with several car insurance companies. Thus, they can help you by providing access to several companies with one auto insurance quote request.

If you need to change your car insurance because a child goes away to college, AlphaSure Affordable Insurance Services can quickly evaluate your entire situation. They will guide you so that you have the right coverage without any overlapping policies. Many times, they can handle the old cancellations, while binding a new policy. This way, there is no lapse in coverage.

Furthermore, the friendly agents at AlphaSure Affordable Insurance Services do not just handle auto insurance. They can also help you shop for home insurance. Bundling your car insurance and home insurance through one company unlocks massive discounts.

Most importantly, you gain incredible peace of mind knowing professionals are there to provide sound advice and guide you in the event of a claim.

Wrapping Up the Car Insurance Puzzle

Navigating the complex car insurance world often feels like wandering blindly through a maze. Rules about primary policies, secondary policies, and pro-rata shares confuse almost everyone. However, you do not have to figure out this complicated puzzle alone.

Always remember that insurance generally follows the vehicle in Texas. Whoever holds the actual title usually dictates which policy pays first. If you face a major life change, such as sending a kid to college or buying a new car, update your policies immediately. Always cancel your old coverage as soon as your new coverage begins.

Above all, reach out to local experts like AlphaSure Affordable Insurance Services. They will gladly help you shop the market. They will find you the best car insurance and home insurance rates while keeping your coverage well aligned. Protect your car, protect your wallet, and drive safely on the Texas roads!

Read More

Does Shopping for Car Insurance Hurt Your Credit Score?

Husband and wife discussing their car insurance at AlphaSure Affordable Insurance in San Antonio

Many drivers dread shopping for new car insurance. You might worry that getting too many quotes will damage your credit score. After all, lenders constantly warn us about the dangers of checking our credit too often. Therefore, it makes perfect sense to wonder if insurance companies follow the same strict rules.

If you want to find the best auto coverage, you need to compare rates. Fortunately, you can relax. Shopping for car insurance will not hurt your credit score.

In this comprehensive guide, we will explore exactly how insurance companies look at your financial history. We will explain the important differences between hard and soft credit pulls. Furthermore, we will show you how to navigate policies with your spouse. Finally, we will explain why partnering with a local independent insurance agent like AlphaSure Affordable Insurance Services is the smartest way to protect your family and your wallet.

Understanding Credit Inquiries

To understand why car insurance quotes are safe for your credit, you first need to know how credit inquiries work. Credit bureaus divide inquiries into two distinct categories: hard inquiries and soft inquiries.

What is a Hard Inquiry?

A hard inquiry happens when you apply for new debt. For example, if you apply for a credit card, a mortgage, or an auto loan, the bank pulls your official credit report. They want to see if you can repay the money you want to borrow.

Hard inquiries do affect your standard FICO credit score. Usually, a single hard pull will drop your score by fewer than five points. This penalty lasts for exactly 12 months. However, the record of the inquiry stays visible on your credit report for a full 24 months.

What is a Soft Inquiry?

On the other hand, a soft inquiry happens when someone checks your credit for a reason other than lending you money. When you check your own credit score on a free app, you trigger a soft inquiry. Employers and landlords also use soft pulls for background checks.

Most importantly, when you ask for a home or car insurance quote, the insurance company performs a soft inquiry. Soft inquiries are completely invisible to lenders. They never impact your FICO score. You can accumulate a dozen soft inquiries in a single week, and your credit score will stay exactly the same.

Rate Shopping: Auto Loans vs. Car Insurance

People often confuse the rules for buying a car with the rules for insuring a car. When you buy a vehicle, you usually need an auto loan. Getting that loan triggers a hard inquiry.

However, the major credit bureaus know that smart consumers shop around for the best interest rates. Therefore, FICO uses a special “de-duplication” window for auto loans. If you apply for a car loan at Wells Fargo, Chase, and Bank of America on the exact same day, FICO counts those three hard pulls as one single event. Depending on the credit model, this shopping window lasts between 14 and 45 days.

In contrast, car insurance shopping has no window and no limits. Because insurance companies only use soft pulls, you never have to worry about a time limit. You can shop for car insurance every single day of the year without ever losing a single credit point.

What is a Credit-Based Insurance Score?

You might wonder why auto insurers care about your credit history if they are not lending you money. They do not care about your ability to repay a loan. Instead, they use your data to create a “credit-based insurance score.”

A credit-based insurance score uses your financial data to predict your future driving behavior. Decades of statistical research show a strong link between credit management and accident risk. People who pay their bills on time and keep their credit card balances low tend to file fewer insurance claims. Conversely, drivers with poor credit file more claims.

Therefore, insurers use your credit-based insurance score to set your monthly premiums. If you have a high score, you usually get lower rates. If your credit score drops, your premiums will likely go up.

The Spouse Strategy in Car Insurance Quotes: Can You Swap Names?

Since credit plays a massive role in insurance pricing, married couples often try to game the system. If you have a great credit score, but your wife has a poor score, you might want to buy the policy using only your name. Is this allowed? Will it save you money?

The short answer is yes, you can put the policy in your name. However, it rarely works the way you hope. Let us look at the rules insurance companies use for married couples.

The Car Insurance Household Driver Rule

Insurance companies legally require you to list every licensed driver who lives in your home on your policy. This rule applies strongly to spouses. You cannot hide your spouse from the insurance company. Once you add your wife to the quote, the insurer’s computer system might check both of your driving records and credit-based insurance scores.

The Primary Insured Loophole

While both of you must appear on the policy, only one person acts as the “Named Insured.” The Named Insured is the primary policyholder. Many insurance algorithms give the primary policyholder’s credit score much more weight.

Therefore, you should always try a simple shopping strategy. Run two identical quotes. For the first quote, list yourself as the primary applicant and your wife as the secondary driver. Next, run a second quote with the roles reversed. Because every insurance carrier uses a slightly different math formula, swapping the primary applicant might save you some money.

Do Not Buy Separate Car Insurance Policies

Some couples get frustrated and try to buy two entirely separate auto policies. They think keeping the bad credit score away from the good credit score will fix the problem. You should never do this.

Married couples earn a massive “marriage discount” with almost every major insurance carrier. Furthermore, when you insure two or more vehicles on the same policy, you earn a multi-car discount. If you split your policies, you lose both of these major discounts. The loss of these discounts will cost you far more money than the penalty for a lower credit score.

The Car Insurance Named Driver Exclusion

If your spouse has truly terrible credit or a horrible driving record, you have one final option. Some states allow you to sign a “Named Driver Exclusion.” This legal document completely removes your spouse from your insurance policy.

However, this option carries a massive risk. If you exclude your spouse, they can never drive your car. If in an emergency your spouse has to drive and crashes, the insurance company will pay nothing. You will pay for all the damages out of your own pocket.

The Best Way to Shop: Use an Independent Car Insurance Agent

Shopping for car insurance takes time, energy, and patience. You will have to fill out endless online forms with each company you check. Thus, the car insurance shopping may be cumbersome or confusing.

Instead of fighting the system alone, you should hire a local expert. When you work with a local independent insurance agent like AlphaSure Affordable Insurance Services, you eliminate the stress of rate shopping entirely.

What is an Independent Car Insurance Agent?

Many insurance agents work directly for one single massive company. We call these “captive agents.” If you visit a State Farm agent, they can only sell you a State Farm policy. If their price is too high, they cannot help you.

In contrast, an independent agent like AlphaSure Affordable Insurance Services works for several insurance companies, not just one. Thus, you will have car insurance options to pick from.

How AlphaSure Saves You Time

When you call AlphaSure Affordable Insurance Services, you only explain your situation one time. You give them your vehicle details, your driver information, and your coverage goals.

Then, the agents at AlphaSure do all the heavy lifting. They plug your information into their advanced comparison systems and run quotes across multiple insurance companies simultaneously. Thus, they quickly identify which carrier offers the best price for your specific situation.

Expert Advice on Household Rules

Independent agents know the complex algorithms inside and out. If you and your spouse have vastly different credit scores, the experts at AlphaSure Affordable Insurance Services know exactly how to structure your application. They will test the quotes with different primary applicants to ensure you get the absolute lowest rate. They also ensure you receive every discount available to you, including marriage, multi-car, or safe driver discounts.

Help with Home Insurance Too

Car insurance is just the beginning. Independent agents also shop for your homeowner’s insurance. Insurers use your credit-based insurance score for home policies as well. AlphaSure Affordable Insurance Services can easily bundle your home and auto policies together. Bundling creates another discount, which should be considered when making the buying decision.

Improve Your Credit for Better Future Car Insurance Rates

While you rely on AlphaSure to find you the best current rate, you should also work on improving your credit score for the future. Every time your policy renews, the car insurance company might check your soft credit score again. If your score improves, your rates might drop.

Here are three simple steps you can take today to build a better credit profile:

First, pay every single bill on time. Payment history makes up the largest chunk of your FICO score. Set up automatic payments to ensure you never miss a due date.

Second, pay down your credit card balances. Credit utilization measures how much debt you carry compared to your total limits. Keep your balances low to see a rapid increase in your credit score.

Third, check your credit reports for errors. You can request free reports from the major bureaus. If you find a mistake, dispute it immediately. Removing an unfair collection account can boost your score overnight.

Conclusion

You never need to fear shopping for car insurance. Because insurance companies only use soft credit inquiries, checking your rates will never damage your credit score. You can safely compare as many carriers as you want.

If you want to maximize your savings without wasting your weekend, let the professionals do the work. A local independent insurance agent like AlphaSure Affordable Insurance Services has the tools, the knowledge, and the partnerships to find you the right car insurance policy. They will navigate the complex rules of credit scores and household drivers for you. Contact an independent agent today and discover how much money you can truly save.

Read More

Car Insurance for a Canada Road Trip: A Real-Life Story

Family driving their minivan-with car insurance from alphasure- out of San Antonio

Road trips create some of the best memories. Recently, a car insurance customer of mine planned the ultimate baseball getaway. He drove all the way from San Antonio, Texas, up north to Detroit, Michigan. He wanted to visit his adult son and catch a great baseball game together. They spent a fun day exploring Detroit and cheering at the ballpark. After that, they decided to keep the adventure going. They drove across the border into Canada to watch the Toronto Blue Jays play.

This spontaneous road trip sounded amazing. However, it brought up an important question before they crossed the border. The customer called me to ask about his auto policy. He wanted to know exactly how his Progressive car insurance policy works while driving in Canada. He did not want to face any legal trouble in a different country. Taking the time to ask this question saved him a lot of stress.

Crossing the Border: Do You Have Car Insurance Coverage?

Many people assume their auto policy stays the same no matter where they drive. For the most part, a standard US auto policy extends your coverage into Canada. Therefore, you do not usually need to buy a separate policy just for a short weekend trip. However, every insurance company handles international travel a little differently.  Plus, Canadian law may have other requirements that need to be addressed.

Because the customer planned to drive his own vehicle into a foreign country, he made the smart choice to call me first. He asked a great question that many travelers forget to ask. We needed to make sure he had the right paperwork before he reached the border crossing. Without the proper documents, Canadian border officials may fine you or turn you around. Fortunately, we quickly sorted out the details. We reviewed his policy documents to ensure he had adequate protection for the long drive.

Adding a Driver to Your Car Insurance

When we reviewed his Progressive car insurance policy, we found a minor detail we needed to fix. The customer planned to share the driving duties with his son. Naturally, they wanted to take turns behind the wheel during the long drive from Detroit to Toronto. Sharing the driving load keeps everyone awake and safe on the highway.

Even though the son no longer lives with his father, Progressive required us to add him as a listed driver on the policy. This was done so that the the Canadian car insurance ID card will list the son as a driver. We added his son to the policy right away. This simple update took only a few minutes, but it provided peace of mind.

The Canadian Non-Resident Liability Card

Next, we had to get the correct proof of insurance. Canada requires specific documentation from foreign drivers. You cannot just show your standard US digital insurance card on your cell phone. Instead, Progressive needed to provide a special document.

This physical document is called a Canada “non-resident” inter-province motor vehicle liability insurance card. It proves to the Canadian government that you carry the required minimum liability limits to drive on their roads. Furthermore, you need this card to cover all drivers listed on the policy. I made a quick phone call to Progressive on behalf of my client. I explained the situation to the representative. Within a few minutes, the representative generated the special Canadian liability card. Progressive sent it straight to the customer’s email inbox. He printed the card out at his hotel, and they were completely ready to go.

Preparing Your Vehicle for an International Trip

Aside from updating your auto policy, you must prepare your vehicle before you drive into a different country. A long road trip puts a lot of stress on your car engine and tires. Therefore, I always tell my clients to get a full mechanical inspection before they leave town.

First, check your tire pressure and tire tread. You need good traction if you encounter rain or bad weather near the Great Lakes. Next, top off all your essential fluids, including your motor oil, coolant, and windshield washer fluid. Furthermore, make sure your windshield wipers work perfectly. My customer drove a reliable truck, but he still checked everything before leaving Texas. Taking these simple steps drastically reduces your chances of a breakdown. When you combine a well-maintained vehicle with solid car insurance coverage, you set yourself up for a highly successful road trip.

Car Insurance Option: Roadside Assistance and Trip Interruption Benefits

Before they hit the open road, we also talked about emergencies. Driving long distances always carries some risk. A flat tire, a dead battery, or a broken engine can quickly ruin a fun vacation. Because of this, I reminded him about the Roadside Assistance coverage on his Progressive car insurance policy. This coverage pays for towing, jump-starts, flat tire changes, and lockout services.

Even better, Progressive offers a fantastic feature called Trip Interruption coverage. If your car breaks down more than one hundred miles from your home, Trip Interruption helps pay for surprise expenses. For example, up to a certain policy limit, it covers hotel rooms, meals, and emergency transportation while a mechanic fixes your car. Since they were traveling hundreds of miles away from San Antonio, this coverage gave them total peace of mind. If a breakdown happened in Canada, they would have benefits that help pay for extra hotel nights.

Enjoying the Game with Total Peace of Mind

Because he called ahead, my customer and his son enjoyed a completely stress-free trip. They crossed the Canadian border without any problems. They showed their Canadian car insurance liability card to the border agents and drove straight to Toronto.

Later, he told me that watching the Blue Jays play in their home stadium was a fantastic experience. They ate great stadium food, watched amazing baseball, and bonded on the open road. More importantly, they never had to worry about what might happen if they had a fender bender or if their car broke down. They knew their auto policy protected them every single step of the way. This real-life story shows exactly why you should always double-check your car insurance policy before a big road trip. A ten-minute phone call can save you thousands of dollars and hours of frustration. Always prepare before you travel.

Why You Need a Local Independent Car Insurance Agent

Dealing with giant insurance companies can feel confusing. You might wait on hold for a long time if you call a 1-800 number. You might talk to a different person every single time you call. This is exactly why you need a local independent car insurance agent.

When you work with a local agent, you get direct, personalized service. As an independent agency, AlphaSure Affordable Insurance Services helps drivers in San Antonio and Laredo find the best possible coverage. We do not work for just one company. Instead, we shop around to compare rates from several different carriers for you. Whether you need cheap car insurance or reliable home insurance, we do all the hard work so you do not have to. When life throws you a curve ball, or when you just want to drive to a baseball game in Canada, we are here to help. Contact AlphaSure Affordable Insurance Services today to review your current policy and get a free quote!

Read More

Car Insurance Myths: Does a Totaled Car Clear Your Loan?

Picture of vehicle rollover and the driver is calling his car insurance company

Have you ever heard the saying that a totaled car equals a paid-off loan? Many drivers believe this common myth. They think that if they crash their vehicle, their car insurance will step in and completely wipe out their remaining loan balance. However, this is rarely true. Let us explore the reality of what happens when you total your car and how you can protect your wallet.

Common Car Insurance Myth

If a vehicle is totaled, the insurance payout will completely wipe out the remaining auto loan or lease balance. People often think standard car insurance acts as a magical eraser for their car debt.

The Car Insurance Reality

Standard car insurance policies do not care about your loan balance. Instead, they pay the Actual Cash Value (ACV) of your vehicle at the time of the loss. Unfortunately, the ACV aggressively factors in depreciation. A new car loses a huge chunk of its value the second you drive it off the dealership lot. Therefore, your insurance company will only pay what the car is worth today, not what you originally paid for it.

The Danger of Being Underwater

Because vehicles lose value so quickly, you might owe more on your loan than the car is actually worth. Financial experts call this being “underwater” on a loan. If you total your car while you are underwater, your standard car insurance, with comprehensive and collision, will not cover the full loan amount. As a result, you have to cover the difference out of your own pocket. Paying thousands of dollars for a car you can no longer drive is a terrible financial burden.

The Solution: Gap Insurance added to the Policy

How can you avoid this expensive trap? You need to specifically carry Gap insurance. Gap coverage pays the difference between your car’s actual cash value and the remaining balance on your auto loan. If you have this specific coverage, you will not have to empty your savings account to pay off a wrecked vehicle. Gap insurance does have restrictions so be sure to talk to your agent about that.

Get Expert Help Today

Finding the right car insurance coverage can feel confusing. Fortunately, you do not have to figure it out alone. You can reach out to a local independent insurance agent like AlphaSure Affordable Insurance Services to help in shopping for car or home insurance. The experts at AlphaSure will review your current policy and help you find a policy that won’t break the bank.

Read More

Texas Car Insurance: Why You Must Beat the Storm Moratoriums

Texas weather changes fast. One minute the sun shines, and the next minute, a flash flood warning flashes on your screen. When severe weather heads your way, you might want to check your car insurance. However, waiting until a storm gets close creates a huge problem. This is because car insurance companies usually put a “binding moratorium” in place. As a result of this moratorium, you could face massive repair bills.

What is a Binding Moratorium in Home and Car Insurance?

First, let us explain what a binding moratorium actually means. A moratorium is simply a temporary freeze on new policies. When the National Weather Service issues a severe storm or flood warning, insurance companies stop selling new car insurance policies in that specific area. In addition, they will not let you change your current policy. For example, you cannot add comprehensive coverage or lower your deductible until the storm completely passes and your vehicle is undamaged.

Why Do Insurance Companies Use These Rules?

You might wonder why insurers use these strict rules. Basically, car insurance exists to protect you from future, unexpected problems. If people only bought coverage when a flood was guaranteed to hit, the insurance companies would stand to suffer huge claims. Therefore, they use moratoriums to keep their business stable.

Why You Need Coverage Early

As a result of these rules, you must set up your insurance policy before the dark clouds roll in. If rising water damages your car, you need comprehensive coverage to pay for the repairs. Sadly, if you try to buy this coverage during a moratorium, the company will say no. Thus, if your car is damaged in the flood, you have to pay the entire repair bill yourself.

How a Local Home and Car Insurance Agent Can Help

To avoid this stressful situation, you should plan ahead. A local independent insurance agent like AlphaSure Affordable Insurance Services can help you shop for the best car or home insurance. We understand Texas weather risks, and we can help find a policy that fits your budget.

Read More

What to Do After a Minor Fender Bender- When to Notify Your Car Insurance

Drivers exchanging car insurance information on the side of the road in downtown san antonio

Getting into a minor fender bender is always stressful. However, knowing exactly what to do next makes a huge difference. If you handle the scene correctly, you will have a much easier time filing a car insurance claim. Follow these simple steps to protect yourself and your vehicle.

Move Your Vehicle and Call the Police

First, check everyone for injuries. If the cars can still drive safely, you must move them out of the traffic lanes. This keeps everyone safe and keeps traffic moving. Next, assess the other driver. If the other person is uncooperative or angry, call the police immediately. Always ask to file an official police report because it provides a reliable record of the crash.

Swap Details and Find Witnesses for a Car Insurance Claim

Always exchange contact information with the other driver. Get their full name, phone number, and current car insurance details. Additionally, look around for anyone who saw the crash happen. Ask for their phone numbers, too. Witnesses can prove exactly what happened if the other driver changes their story later on.

Document the Accident Scene

Before you leave the area, pull out your smartphone. Take clear pictures of the damage on both cars. Also, snap a quick photo of the other driver’s license plate and insurance card. Furthermore, if you use a dash cam in your vehicle, save the video file right away. Video proof is the absolute best way to speed up your car insurance claim.

Talk to the Car Insurance Company

If the other driver is clearly at fault, ask them to file a claim with their company right then. Insist that both of you give a recorded statement to the insurance adjuster while the details are fresh. This locks in their story.

However, you must be careful with your own words. Stick only to the facts. Never admit fault, and do not tell the adjuster you are completely uninjured. Adrenaline hides physical pain, and soft tissue injuries often show up a day or two later.

When to Use Your Own Car Insurance

Sometimes, you run into trouble with the other driver’s company. For instance, the damages might exceed your collision deductible, making it smarter to file the claim with your own policy. Other times, you might discover the at-fault driver let their policy lapse. If their company denies the claim, your uninsured motorist coverage will step in to help pay for the damage.

Find the Right Coverage with a Local Agent

Finally, make sure you have the right protection long before an accident happens. Shopping for car insurance or home insurance is simple when you use a local independent insurance agent. The dedicated team at AlphaSure Affordable Insurance Services can help you compare different options. We work hard to find you the best rates and the exact coverage you need. Reach out to AlphaSure Affordable Insurance Services today to review your current policy and drive with true peace of mind.

Read More

Why Your E-Bike Needs Its Own Insurance Policy

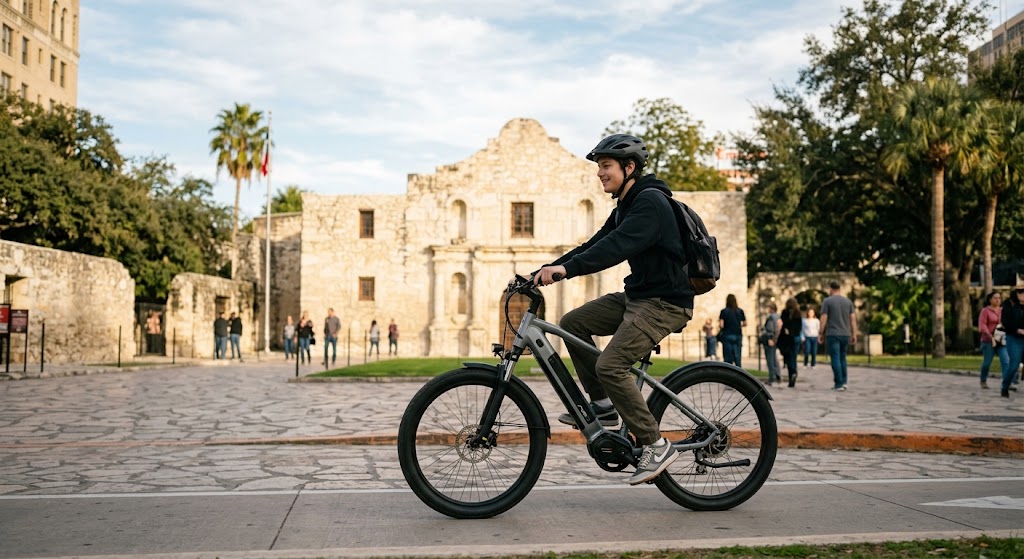
Teen riding an e-bike not covered in car insurance he is riding in front of the Alamo in San Antonio

E-bikes are incredibly fun and save you money on gas. However, many riders make a huge mistake. They assume their standard home or car insurance will pay for e-bike accidents. Unfortunately, this is rarely true. Let’s look at why you need a dedicated specialty e-bike insurance policy.

Home and Car Insurance Exclusions

First, insurance companies usually group e-bikes with motorcycles. Because e-bikes have an electric motor, most home or renters insurance policies will not cover them. If you crash into a pedestrian while riding on the sidewalk, your home policy will likely deny the claim. Consequently, you would have to pay their medical bills out of your own pocket. In addition, a standard car insurance policy only covers vehicles with four wheels that are registered to drive on public roads. The auto policy excludes two or three wheeled vehicles. Therefore, your car insurance will not step in to help you either.

The Specialty Insurance Option

On the other hand, a specialty e-bike policy gives you exactly what you what your car insurance lacks. Here are four main reasons to get one:

1. Liability Protection If you hurt someone or dent a parked car, an e-bike policy pays for damage or injuries to the other party. Thus, it protects your personal savings or assets from expensive lawsuits.

2. Better Theft Coverage Thieves absolutely love e-bikes. Home insurance rarely covers theft when you lock your bike outside a store or office. Furthermore, home deductibles are very high. E-bike policies cover theft anywhere with a much lower deductible.

3. Collision Damage Repairs If you wipe out and break your expensive bike frame, home or car insurance will not pay to fix it. A special e-bike policy with collision coverage will pay to repair your damaged bike after an accident.

4. Uninsured Motorist Protection If an uninsured driver hits you, you could face massive medical bills. Specialty e-bike policies with uninsured/under-insured motorist coverage can pay for your injuries when the at-fault driver lacks good car insurance.

Seek Guidance and a Quote for E-Bike or Car Insurance

Navigating these tricky coverage rules is tough. For this reason, you should always talk to a local expert. An independent car insurance agency like AlphaSure Affordable Insurance Services can make the entire process simple. They know the San Antonio and Laredo markets inside and out. Whether you need coverage for a new e-bike or you just want to find better rates on your car insurance, they do the hard work for you. They compare quotes from multiple companies to find your perfect fit.

In conclusion, do not leave your financial health to chance. Get a dedicated e-bike policy today. Reach out to AlphaSure Affordable Insurance Services to protect your ride, your home, and your cars.

Read More

Why You Should Never Hide a Driver on Your Car Insurance Policy

Vehicle was crashed by an undisclosed driver on a car insurance policy in san Antonio

Everyone wants to save money on car insurance. Sometimes, people think about leaving a regular driver off their policy to cut costs. They do this because, for example, a teen driver or a family member with speeding tickets costs more to insure.

However, doing this is a huge mistake!

Is It Legal to Withhold Household Members from Your Car Insurance?

No, it is not legal. When you buy car insurance, you sign an application. You must tell the truth. If you hide a regular driver, you commit insurance fraud. Experts call this “rate evasion.” Insurance companies base your price on everyone who lives with you and drives your vehicles. Therefore, lying about who lives in your house breaks the law.

The Costly Consequences

What happens if the car insurance company catches you? The results can be very serious.

First, your insurance company will deny your claims. If the hidden driver crashes your car, you pay for everything out of your own pocket. You will pay for the other person’s medical bills, and you will pay for their car repairs.

Second, the company will cancel your policy. Having a canceled policy on your record makes finding new coverage at an affordable price very hard.

Finally, you might face criminal charges. Because this act counts as fraud, Texas law can punish you with fines or jail time.

The Right Way to Save on Car Insurance

What if you have a risky driver at home, but they never drive your car? Texas law gives you a safe choice called a “Named Driver Exclusion.”

With this rule, you sign an Named Driver Exclusion form. This document states that the excluded person has absolutely zero coverage. It safely lowers your price. However, you must remember that the excluded person can never drive your car. This is because, if they drive the car and crash, you will get no coverage from the insurance company. Thus, you will pay for all medical bills and property damage out of your own pocket.

How to Find Better Rates

Finding cheap coverage does not mean you must break the rules. You just need to shop around.

A local independent insurance agent can help you do this safely. For example, AlphaSure Affordable Insurance Services has helped drivers in San Antonio and Laredo find great rates since 2003. We know the Texas market well. We can check prices from many different companies at once. Let us help you find affordable car or home insurance the right way, without the risk.

Read More

The Hidden Trap of Letting a Dealership Handle Your Car Insurance

New vehicle crashes into a guard rail that has no collision coverage on the car insurance policy

Imagine buying a shiny new vehicle. You drive off the lot feeling great about your purchase. Additionally, you are pleasantly surprised that there was not much of an impact on the car insurance premium! A few months later, you slide off the road and hit a guardrail and total your car! You immediately call to file a claim on your insurance, only to hear shocking news. You have no collision coverage.

How did this happen? In a recent real-life scenario, someone added a new vehicle to a buyer’s car insurance policy with only comprehensive coverage. The insurance company confirmed they did not process the change. The local agency did not do it, either. Ultimately, it seems the auto dealership made the change, on behalf of the buyer. To keep the monthly payment low and save the sale of the new car, the dealer likely dropped the vital collision coverage.

The Ulterior Motive of Letting the Dealership Handle Your Car Insurance

Therefore, letting an auto dealership make changes to your car insurance policy is a massive financial risk. Dealerships primarily want to sell cars. They do not prioritize your financial safety. When you let a dealer login into your online policy servicing account, you give up control. For instance, they might drop an important coverage just to get you out the door. As a result, you pay the ultimate price when an accident happens.

Do Not Let Anyone Handle Your Car Insurance

To protect your family, you must handle your policy updates personally. Even better, it is a great idea to talk to a local independent insurance agent like AlphaSure Affordable Insurance Services.

An independent agent works for you, not the car dealership. Furthermore, an independent agency like AlphaSure Affordable Insurance Services can help you shop for both car or home insurance. Because they work with multiple insurance carriers, they compare different plans from top companies to find you the exact coverage you need at the best possible price. They will take the time to go over policy coverage, deductibles and limitations so that you will feel confident with the policy you have.

In conclusion, always take charge of your car insurance. When you buy your next vehicle, call your local independent agent directly and drive away with true peace of mind.  Be sure to talk to a licensed insurance agent to discuss what your policy covers and the premiums.

Read More