HOW CAN WE HELP YOU?

Click to Call (Laredo) Click to Call (San Antonio)

201 W Del Mar Blvd, Suite 20
Laredo, TX 78041

Get Directions

3740 Colony Dr, Suite 280
San Antonio, TX 78230

Get Directions

AlphaSure Affordable Insurance Svcs Blog

Does Shopping for Car Insurance Hurt Your Credit Score?

Husband and wife discussing their car insurance at AlphaSure Affordable Insurance in San Antonio

Many drivers dread shopping for new car insurance. You might worry that getting too many quotes will damage your credit score. After all, lenders constantly warn us about the dangers of checking our credit too often. Therefore, it makes perfect sense to wonder if insurance companies follow the same strict rules.

If you want to find the best auto coverage, you need to compare rates. Fortunately, you can relax. Shopping for car insurance will not hurt your credit score.

In this comprehensive guide, we will explore exactly how insurance companies look at your financial history. We will explain the important differences between hard and soft credit pulls. Furthermore, we will show you how to navigate policies with your spouse. Finally, we will explain why partnering with a local independent insurance agent like AlphaSure Affordable Insurance Services is the smartest way to protect your family and your wallet.

Understanding Credit Inquiries

To understand why car insurance quotes are safe for your credit, you first need to know how credit inquiries work. Credit bureaus divide inquiries into two distinct categories: hard inquiries and soft inquiries.

What is a Hard Inquiry?

A hard inquiry happens when you apply for new debt. For example, if you apply for a credit card, a mortgage, or an auto loan, the bank pulls your official credit report. They want to see if you can repay the money you want to borrow.

Hard inquiries do affect your standard FICO credit score. Usually, a single hard pull will drop your score by fewer than five points. This penalty lasts for exactly 12 months. However, the record of the inquiry stays visible on your credit report for a full 24 months.

What is a Soft Inquiry?

On the other hand, a soft inquiry happens when someone checks your credit for a reason other than lending you money. When you check your own credit score on a free app, you trigger a soft inquiry. Employers and landlords also use soft pulls for background checks.

Most importantly, when you ask for a home or car insurance quote, the insurance company performs a soft inquiry. Soft inquiries are completely invisible to lenders. They never impact your FICO score. You can accumulate a dozen soft inquiries in a single week, and your credit score will stay exactly the same.

Rate Shopping: Auto Loans vs. Car Insurance

People often confuse the rules for buying a car with the rules for insuring a car. When you buy a vehicle, you usually need an auto loan. Getting that loan triggers a hard inquiry.

However, the major credit bureaus know that smart consumers shop around for the best interest rates. Therefore, FICO uses a special “de-duplication” window for auto loans. If you apply for a car loan at Wells Fargo, Chase, and Bank of America on the exact same day, FICO counts those three hard pulls as one single event. Depending on the credit model, this shopping window lasts between 14 and 45 days.

In contrast, car insurance shopping has no window and no limits. Because insurance companies only use soft pulls, you never have to worry about a time limit. You can shop for car insurance every single day of the year without ever losing a single credit point.

What is a Credit-Based Insurance Score?

You might wonder why auto insurers care about your credit history if they are not lending you money. They do not care about your ability to repay a loan. Instead, they use your data to create a “credit-based insurance score.”

A credit-based insurance score uses your financial data to predict your future driving behavior. Decades of statistical research show a strong link between credit management and accident risk. People who pay their bills on time and keep their credit card balances low tend to file fewer insurance claims. Conversely, drivers with poor credit file more claims.

Therefore, insurers use your credit-based insurance score to set your monthly premiums. If you have a high score, you usually get lower rates. If your credit score drops, your premiums will likely go up.

The Spouse Strategy in Car Insurance Quotes: Can You Swap Names?

Since credit plays a massive role in insurance pricing, married couples often try to game the system. If you have a great credit score, but your wife has a poor score, you might want to buy the policy using only your name. Is this allowed? Will it save you money?

The short answer is yes, you can put the policy in your name. However, it rarely works the way you hope. Let us look at the rules insurance companies use for married couples.

The Car Insurance Household Driver Rule

Insurance companies legally require you to list every licensed driver who lives in your home on your policy. This rule applies strongly to spouses. You cannot hide your spouse from the insurance company. Once you add your wife to the quote, the insurer’s computer system might check both of your driving records and credit-based insurance scores.

The Primary Insured Loophole

While both of you must appear on the policy, only one person acts as the “Named Insured.” The Named Insured is the primary policyholder. Many insurance algorithms give the primary policyholder’s credit score much more weight.

Therefore, you should always try a simple shopping strategy. Run two identical quotes. For the first quote, list yourself as the primary applicant and your wife as the secondary driver. Next, run a second quote with the roles reversed. Because every insurance carrier uses a slightly different math formula, swapping the primary applicant might save you some money.

Do Not Buy Separate Car Insurance Policies

Some couples get frustrated and try to buy two entirely separate auto policies. They think keeping the bad credit score away from the good credit score will fix the problem. You should never do this.

Married couples earn a massive “marriage discount” with almost every major insurance carrier. Furthermore, when you insure two or more vehicles on the same policy, you earn a multi-car discount. If you split your policies, you lose both of these major discounts. The loss of these discounts will cost you far more money than the penalty for a lower credit score.

The Car Insurance Named Driver Exclusion

If your spouse has truly terrible credit or a horrible driving record, you have one final option. Some states allow you to sign a “Named Driver Exclusion.” This legal document completely removes your spouse from your insurance policy.

However, this option carries a massive risk. If you exclude your spouse, they can never drive your car. If in an emergency your spouse has to drive and crashes, the insurance company will pay nothing. You will pay for all the damages out of your own pocket.

The Best Way to Shop: Use an Independent Car Insurance Agent

Shopping for car insurance takes time, energy, and patience. You will have to fill out endless online forms with each company you check. Thus, the car insurance shopping may be cumbersome or confusing.

Instead of fighting the system alone, you should hire a local expert. When you work with a local independent insurance agent like AlphaSure Affordable Insurance Services, you eliminate the stress of rate shopping entirely.

What is an Independent Car Insurance Agent?

Many insurance agents work directly for one single massive company. We call these “captive agents.” If you visit a State Farm agent, they can only sell you a State Farm policy. If their price is too high, they cannot help you.

In contrast, an independent agent like AlphaSure Affordable Insurance Services works for several insurance companies, not just one. Thus, you will have car insurance options to pick from.

How AlphaSure Saves You Time

When you call AlphaSure Affordable Insurance Services, you only explain your situation one time. You give them your vehicle details, your driver information, and your coverage goals.

Then, the agents at AlphaSure do all the heavy lifting. They plug your information into their advanced comparison systems and run quotes across multiple insurance companies simultaneously. Thus, they quickly identify which carrier offers the best price for your specific situation.

Expert Advice on Household Rules

Independent agents know the complex algorithms inside and out. If you and your spouse have vastly different credit scores, the experts at AlphaSure Affordable Insurance Services know exactly how to structure your application. They will test the quotes with different primary applicants to ensure you get the absolute lowest rate. They also ensure you receive every discount available to you, including marriage, multi-car, or safe driver discounts.

Help with Home Insurance Too

Car insurance is just the beginning. Independent agents also shop for your homeowner’s insurance. Insurers use your credit-based insurance score for home policies as well. AlphaSure Affordable Insurance Services can easily bundle your home and auto policies together. Bundling creates another discount, which should be considered when making the buying decision.

Improve Your Credit for Better Future Car Insurance Rates

While you rely on AlphaSure to find you the best current rate, you should also work on improving your credit score for the future. Every time your policy renews, the car insurance company might check your soft credit score again. If your score improves, your rates might drop.

Here are three simple steps you can take today to build a better credit profile:

First, pay every single bill on time. Payment history makes up the largest chunk of your FICO score. Set up automatic payments to ensure you never miss a due date.

Second, pay down your credit card balances. Credit utilization measures how much debt you carry compared to your total limits. Keep your balances low to see a rapid increase in your credit score.

Third, check your credit reports for errors. You can request free reports from the major bureaus. If you find a mistake, dispute it immediately. Removing an unfair collection account can boost your score overnight.

Conclusion

You never need to fear shopping for car insurance. Because insurance companies only use soft credit inquiries, checking your rates will never damage your credit score. You can safely compare as many carriers as you want.

If you want to maximize your savings without wasting your weekend, let the professionals do the work. A local independent insurance agent like AlphaSure Affordable Insurance Services has the tools, the knowledge, and the partnerships to find you the right car insurance policy. They will navigate the complex rules of credit scores and household drivers for you. Contact an independent agent today and discover how much money you can truly save.

Read More

Texas Car Insurance: Why You Must Beat the Storm Moratoriums

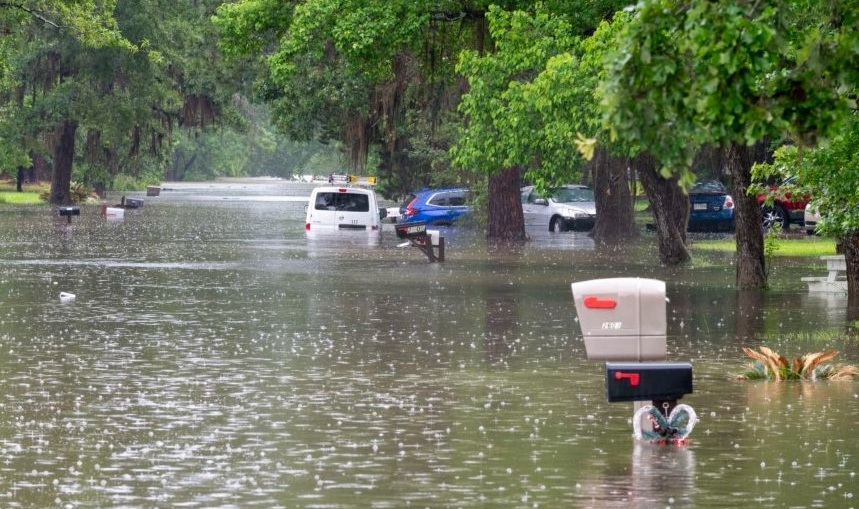
Texas weather changes fast. One minute the sun shines, and the next minute, a flash flood warning flashes on your screen. When severe weather heads your way, you might want to check your car insurance. However, waiting until a storm gets close creates a huge problem. This is because car insurance companies usually put a “binding moratorium” in place. As a result of this moratorium, you could face massive repair bills.

What is a Binding Moratorium in Home and Car Insurance?

First, let us explain what a binding moratorium actually means. A moratorium is simply a temporary freeze on new policies. When the National Weather Service issues a severe storm or flood warning, insurance companies stop selling new car insurance policies in that specific area. In addition, they will not let you change your current policy. For example, you cannot add comprehensive coverage or lower your deductible until the storm completely passes and your vehicle is undamaged.

Why Do Insurance Companies Use These Rules?

You might wonder why insurers use these strict rules. Basically, car insurance exists to protect you from future, unexpected problems. If people only bought coverage when a flood was guaranteed to hit, the insurance companies would stand to suffer huge claims. Therefore, they use moratoriums to keep their business stable.

Why You Need Coverage Early

As a result of these rules, you must set up your insurance policy before the dark clouds roll in. If rising water damages your car, you need comprehensive coverage to pay for the repairs. Sadly, if you try to buy this coverage during a moratorium, the company will say no. Thus, if your car is damaged in the flood, you have to pay the entire repair bill yourself.

How a Local Home and Car Insurance Agent Can Help

To avoid this stressful situation, you should plan ahead. A local independent insurance agent like AlphaSure Affordable Insurance Services can help you shop for the best car or home insurance. We understand Texas weather risks, and we can help find a policy that fits your budget.

Read More

Roof Age and Home Insurance in San Antonio: Why a 15-Year-Old Roof Could Cost You Coverage

The 15-Year Mark That Could Cost You Thousands

Picture this. Hail tears through your San Antonio neighborhood, and your roof takes a beating. You call your insurance company expecting a check to cover a full replacement. Instead, you get a fraction of what it actually costs, because somewhere in your policy’s fine print, your roof crossed a threshold you never knew existed.

What Actually Happens at 15 Years

Many Texas home insurance policies quietly shift roof coverage from full replacement cost to actual cash value once a roof hits around fifteen years old. Actual cash value means the insurer subtracts depreciation from the payout, so instead of covering the full cost of a new roof, you receive only what your old, worn roof was actually worth at the time of the claim.

Why This Catches San Antonio Homeowners Off Guard

If your neighborhood hasn’t seen a serious hailstorm in years, it’s easy to assume your roof is fine simply because nothing has gone wrong yet. Meanwhile, your policy’s coverage terms may have quietly shifted at renewal without much notice. The gap between a full replacement payout and a depreciated actual cash value payout can run into the thousands of dollars.

How Insurers Typically Structure This

  • Roofs under 10 years old generally qualify for full replacement cost coverage
  • Roofs between 10 and 15 years may see rate increases or required inspections
  • Roofs 15 to 20 years old often shift to actual cash value, or coverage may be declined for new policies entirely
  • Roofs over 20 years may become difficult to insure without specialty carriers

What San Antonio Homeowners Should Do

Check Your Roof’s Actual Age

If you don’t know when your roof was last replaced, this is worth confirming through inspection records, past permits, or a professional roof assessment.

Ask Your Agent Directly About Your Coverage Type

Don’t assume your policy still provides full replacement cost. Ask specifically whether your roof coverage has shifted to actual cash value at your last renewal.

Consider Your Options Before a Storm Hits

Some carriers still offer full replacement cost coverage on older roofs, particularly if the roof is well maintained. An independent agent can help you compare options rather than assuming your current carrier is your only choice.

This connects to the broader coverage awareness we’ve discussed for San Antonio homeowners, including our post on how overhanging trees affect your roof and your coverage, since both come down to the same idea: insurers are paying closer attention to roof condition than ever before.

AlphaSure Affordable Insurance Services helps San Antonio and Laredo homeowners understand exactly how roof age affects their coverage before a storm forces the question. As an independent agency, we compare multiple carriers to find options that fit older roofs too. Call or visit our San Antonio office today to review your policy.

Read More

Does Car Insurance Cover if You Accidentally Crash Into Your Own House?

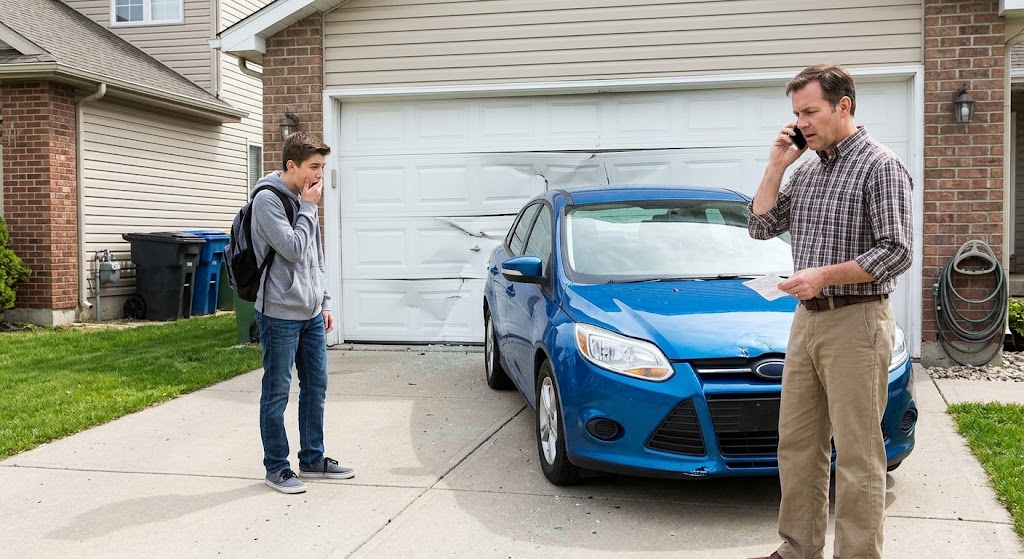
Person calling the car insurance company to file a claim in San Antonio

Picture this. Your teen son just got his driver’s license. You did what you were supposed to do and added him to your car insurance policy. Now, he gets in his car to go to school. In a big rush, he accidentally shifts into drive instead of reverse. Suddenly, he crashes right into your house!

You feel glad because you already added the new driver to your car insurance. However, a big question remains. Who will pay for the damage to the house? Will your car insurance pay, or will your home insurance step in?

Let us clear up the confusion.

Why Car Insurance Will Not Pay for Damages to the House

First, you must understand how car insurance works. When you buy auto liability insurance coverage, it pays for damage you cause to other people’s property. Therefore, it will not pay for damage to your own property. Because you own the house, the liability part of your car insurance policy excludes it. Your car insurance will never write a check to fix damages to your own garage or living room.

Your Home Not Car Insurance Saves the Day

Instead, your home insurance policy will cover the damage to your house. Standard home policies cover damage caused by vehicle impact. Consequently, you will need to file a claim with your home insurance company. Keep in mind, you must pay your home deductible before the policy pays for the actual repairs. Thus, it is always a good idea to get repair estimates from reputable contractors before filing the claim.

What About the Damaged Car?

Even though car insurance does not cover the house, it still plays a role in this accident. If you bought collision coverage, your car insurance will pay to fix the damaged car. Again, you will have to pay your auto insurance deductible first. As a result, you will end up paying two separate deductibles since you must file two separate claims.

Find the Home or Car Insurance Coverage Today

Dealing with accidents always feels stressful. For this reason, you should work with a trusted expert to make sure you are covered. A local independent insurance agent like AlphaSure Affordable Insurance Services can help you review your options. They can shop around for car insurance and home insurance rates for you. Because they work with many different companies, they easily find policies that fit your budget.

Read More

Does Home Insurance Cover in Texas Floods? What You Need to Know

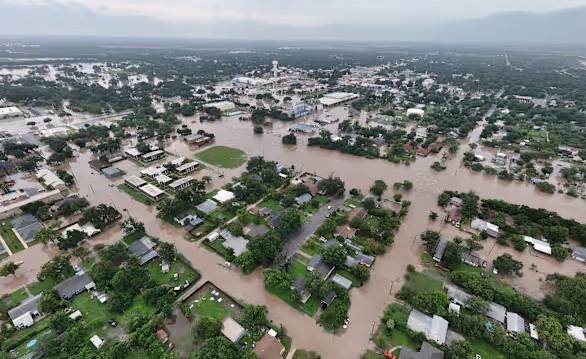
Homes flooded near San Antonio Texas home insurance does not cover flood

Recent storms and heavy rainfall across Texas have left many homeowners dealing with flooding homes. As cleanup efforts begin, one critical question comes up again and again: Does home insurance cover flood damage?

The short answer is no. Standard homeowners insurance policies do not cover damage caused by flood or rising water. 

Understanding how your policy handles water damage can save you from financial disaster. Here is what you need to know about flood risks, water damage coverage, and how to make sure your home is protected against a Texas flood.

Home Insurance and Internal and External Water Damage

Insurance companies look carefully at where the water comes from before they pay a claim. The main rule depends on whether the water started inside or outside your house.

1. Water Damage Covered by Home Insurance

A properly endorsed standard home insurance policy will covers water damage if it happens suddenly from inside the building. Covered situations typically include:

  • A sudden ruptured pipe or broken water line within your home.
  • An overflowing washing machine or water heater.
  • Rainwater that enters through a roof damaged by high winds during a storm.

2. Water Damage That Requires Flood Insurance

If water touches the ground outside before entering your house, home insurance companies may consider it a flood. Thus, a standard home insurance will not cover this damage. You need a separate flood insurance policy to cover flooding events live we’ve seen in the Texas Hill Country.

Why Relying on Government Disaster Aid Is Risky

Many homeowners believe the federal government will cover all repairs after a flood. However, federal disaster assistance only becomes available under certain circumstances. Unfortunately, not every homeowner qualifies for federal flood insurance aid.

Even when disaster aid is available, it often comes as a low-interest loan from the Small Business Administration (SBA). You must repay these loans over time, which adds another monthly bill when you are trying to rebuild. Because of this, buying a dedicated flood policy remains the best way to protect your savings.

Options for Flood Coverage in Texas

Texas homeowners can secure flood coverage through two main channels:

  1. The National Flood Insurance Program (NFIP): Managed by FEMA and sold through licensed insurance agents. It offers up to $250,000 in building coverage and up to $100,000 for personal items. Keep in mind that the NFIP usually enforces a 30-day waiting period before your policy goes into effect.
  2. Private Flood Insurance: Offered by private insurance companies. These policies can provide higher coverage limits, shorter waiting periods, and replacement cost coverage for your belongings.

How an Independent Insurance Agent Helps You Shop

Navigating home insurance and flood policies can feel confusing, especially when weather patterns change quickly. Working with a local independent insurance agency, such as AlphaSure Affordable Insurance Services, makes the process simple and efficient.

Unlike captive insurance agents who work for only one big company, an independent agent works for several companies. Thus, a local independent agency helps in many ways.

  • Access to Multiple Carriers: Independent agents compare rates and coverage options from multiple top-rated home insurance providers at once to find the best value for your budget.
  • Local Expertise: A local agency allows a personal touch. You can always meet face to face to review coverages and explanation different options. There is a local office in San Antonio and Laredo, TX.
  • Custom Bundling: An agent can review both your home insurance and auto insurance policies at the same time. Sometimes, combining your car and home coverage with the same company unlocks substantial multi-policy discounts.
  • Personal Advocacy: If you ever need to file a claim after a storm, your local agent helps guide you through the claims process.

Finding the right coverage does not have to be overwhelming. Partnering with a trusted local team helps ensure your home, vehicles, and financial security stay protected through every season.

Read More

Why Did My Fixed Mortgage Payment Go Up? It could be because of the home insurance.

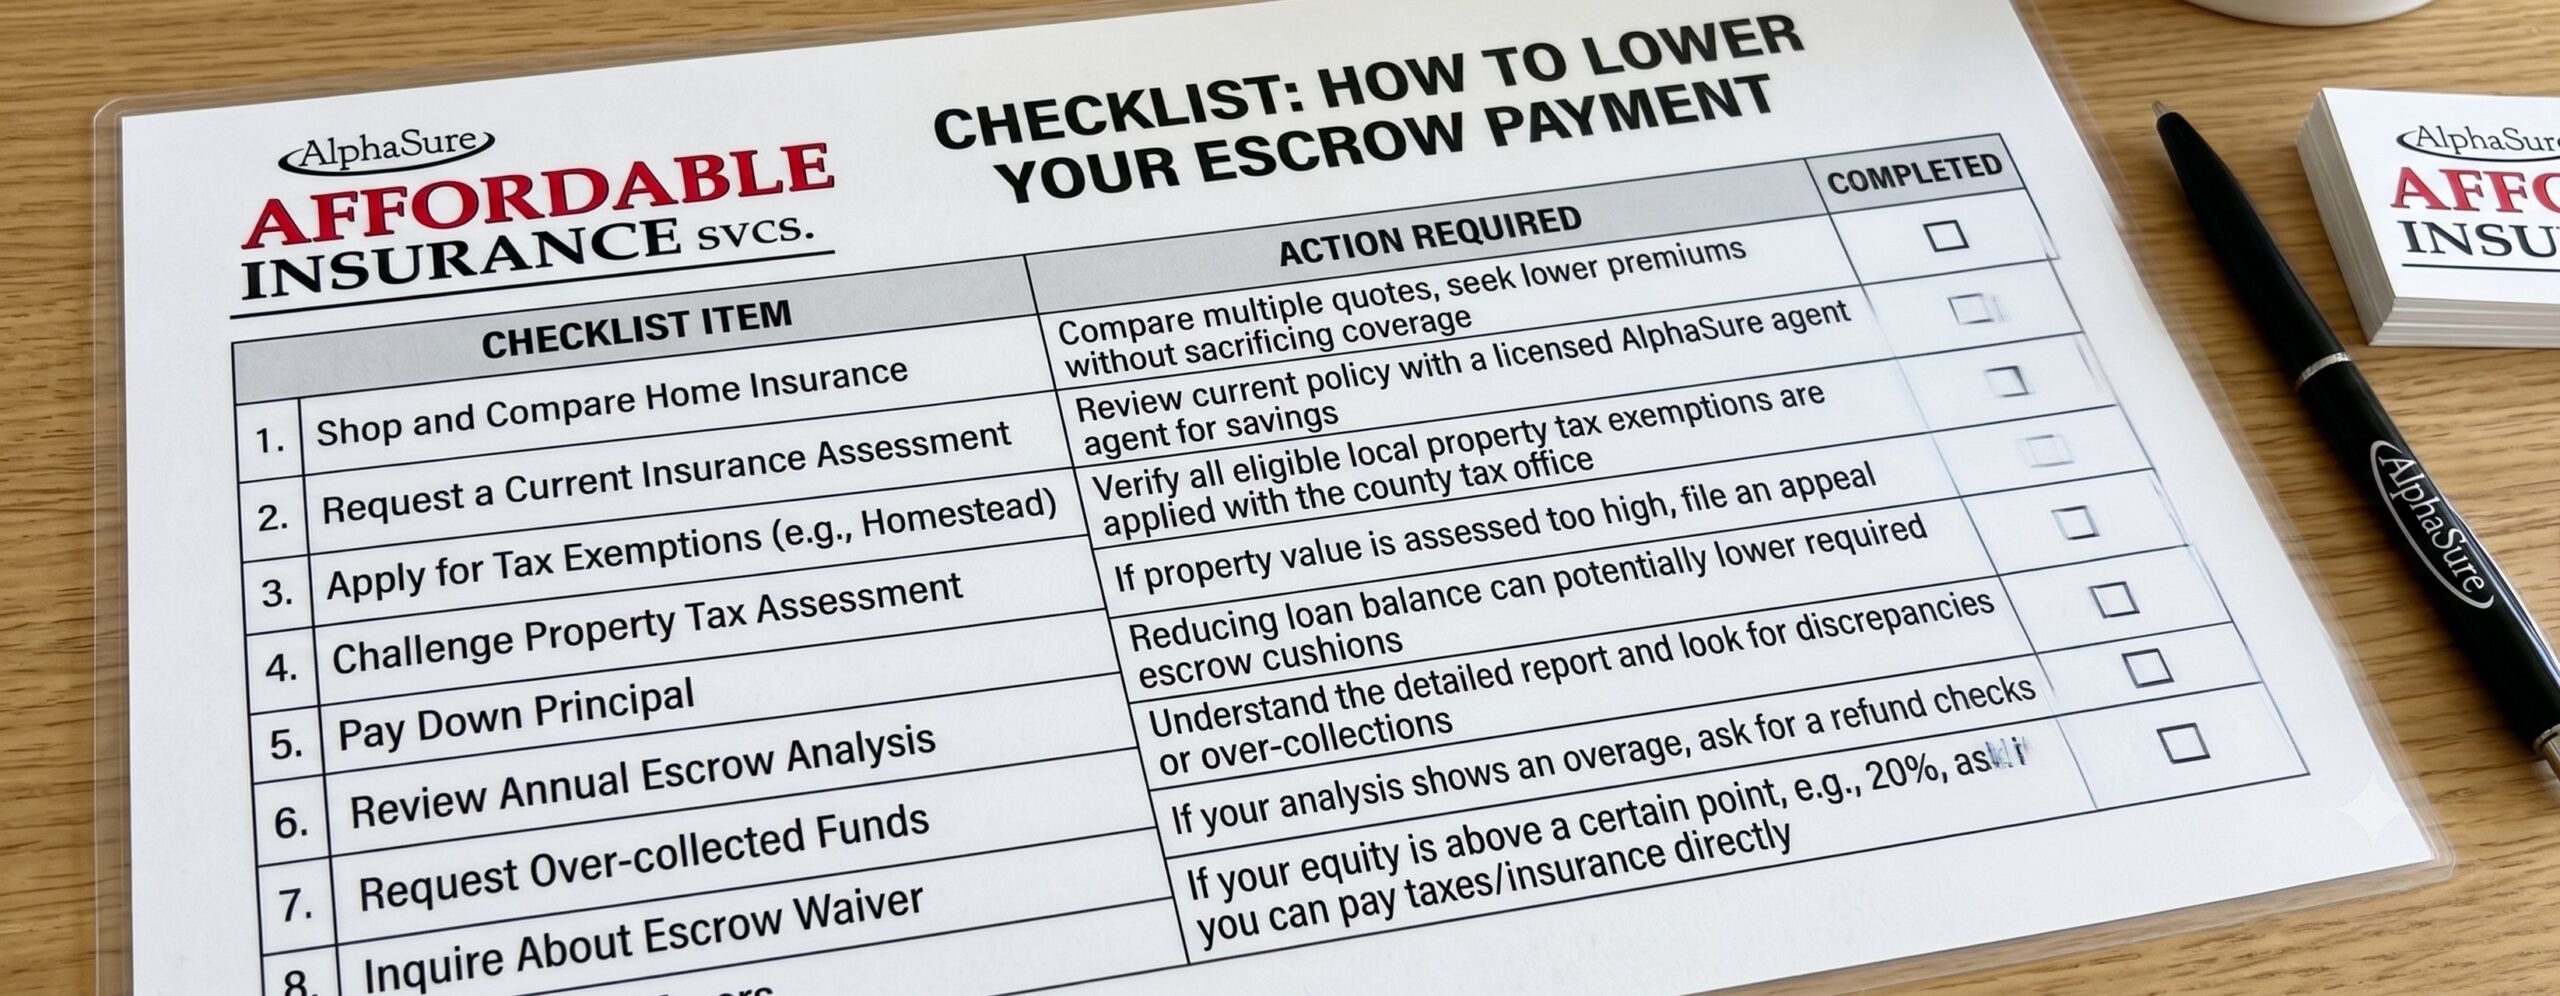
Checklist showing how to lower escrows cost including home insurance

Why Did My Fixed Mortgage Payment Go Up? It could be because of the home insurance.

Have you ever opened your monthly mortgage statement and received a shocking surprise? Your monthly payment went up, but you have a fixed interest rate. How can that happen? A fixed-rate loan means your principal and interest payments never change. Therefore, if your total payment increased, it means either your home insurance or your property taxes (or both!) went up.

Most home loans use an escrow account. Your lender collects extra money each month to pay your annual tax and home insurance bills. When these bills rise, your escrow account falls short, and your lender raises your monthly payment to cover the gap.

The Good News about Shopping for Home Insurance

If a rising insurance premium caused your higher payment, you have options. Many homeowners believe they must wait until their current policy expires to switch companies. This is a myth! You can shop for new home insurance at any time.

Consequently, if you find a better home insurance rate, you can switch immediately. Your old insurance company will refund the unused portion of your premium on a prorated basis. Thus, that refund goes right back into your pocket or your escrow account, helping lower your costs.

💡 Smart Shopper Tip: Check Your Homestead Exemption

Before you change anything, check your property tax status. If you live in the home as your primary residence, make sure you have filed for a homestead exemption with your county tax office. This special tax exemption can lower your home’s taxable value and cap how much your property taxes can rise each year. It is a quick step that saves hundreds of dollars annually.

Work with a Local Independent Home Insurance Agent

Shopping for home insurance on your own can feel overwhelming and take hours. Instead, work with a local independent insurance agent like AlphaSure Affordable Insurance Services. Independent agents do not work for just one big insurance company. Instead, they compare quotes from several top-rated providers.

Don’t let a rising mortgage payment ruin your budget. Check your tax exemptions today and reach out to a local independent agent to start saving on your home insurance.

Read More

Home Insurance- Cut Tree Branches to Lower Insurance Premium

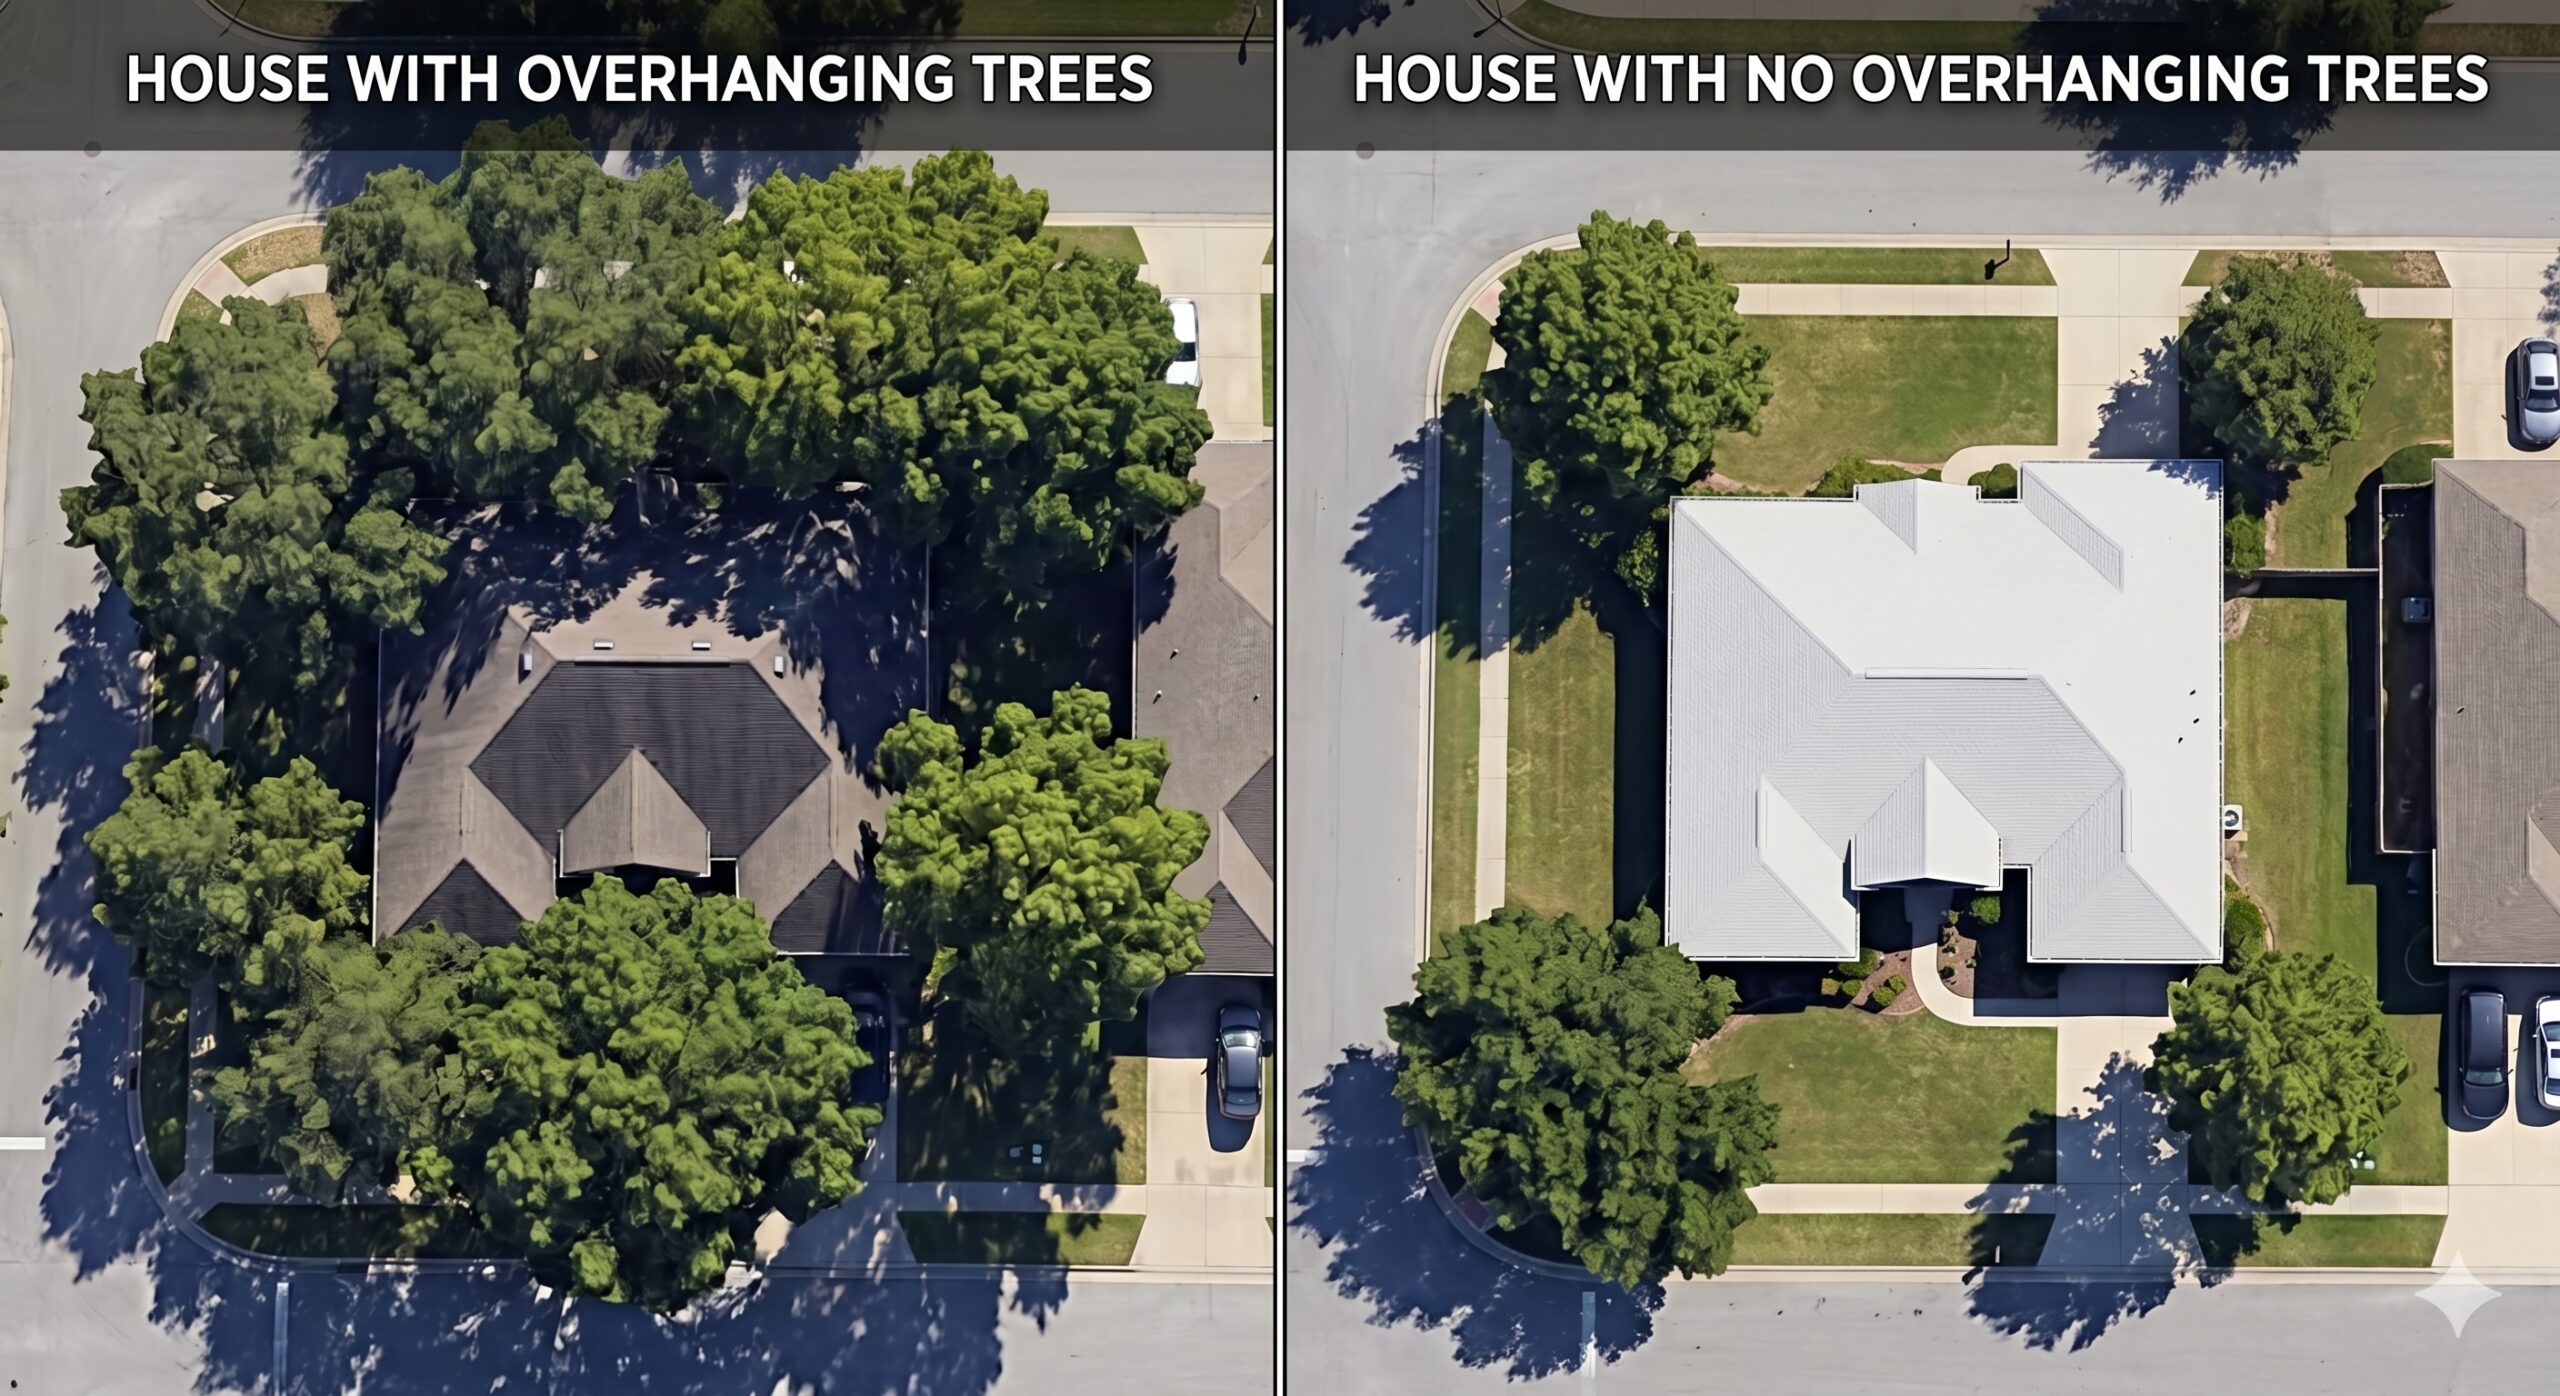
two houses in San Antonio Tx-the one on the right has overhanging trees and the one on the left has no overhanging trees- home insurance companies prefer no overhanging trees

Have you looked out at your yard lately? If you see large tree branches hanging over your roofline, it might be time to hire a tree trimmer. In Texas, keeping your trees neat is not just about curb appeal, it also plays a huge role in your home insurance eligibility and possibly, your wallet.

Trimming tree branches away from your roofline drastically improves your home insurance eligibility. In fact, it might even help you find a lower priced home policy.

Texas Home Insurance Companies Care About Your Trees

Texas weather is highly unpredictable. From intense windstorms and heavy hail to hurricanes, our homes take a beating every year. Thus, when severe weather hits, overgrown branches become major hazards.

First, strong winds can snap heavy limbs, sending them crashing directly into your roof. This causes severe structural destruction and expensive leaks. Second, constant rubbing from nearby branches can scrape away the protective granules on your roof shingles over time. This mechanical friction weakens your roof long before a storm even arrives. Finally, overhanging branches drop leaves and twigs that clog your gutters, leading to rot and water damage.

The Eye in the Sky: How Home Insurance Companies Spot Overgrown Trees

You might think an insurance company will only notice your trees if you file a claim, but that is no longer the case. Today, technology allows providers to view your property from above.

Many insurance companies now use high-resolution satellite images and aerial photography via drones to review your roof layout. Sometimes, they use these images to check the condition of your home before they even agree to cover your home. Thus, the number of home insurance quotes that are available becomes limited. As a result, you may not be getting the best priced policy.

Furthermore, carriers rely heavily on a post-bind inspection. This is a formal property review that happens right after your policy starts and sometimes before the next renewal. Between the overhead satellite data and the detailed post-bind inspection reports, insurers will easily spot any branches hovering too close to your house. If they flag your property as a high risk, they can choose cancel your policy during the initial underwriting period or non-renew your policy at expiration.

The Impact on Home Insurance Eligibility and Rates

Can trimming your trees really save you money? Yes, it absolutely can.

  • Better Eligibility: Many insurance companies in Texas will deny coverage or refuse to renew a policy if their satellite data shows overhanging branches. Trimming your trees keeps your home eligible for coverage in a tough market.
  • Lower Premiums: Many insurance providers offer better home insurance rates for homes with a roof in good condition and no overhanging trees.
  • Avoiding Claims: The cheapest claim is the one you never have to file. Keeping branches clear prevents costly claims, which helps keep your long-term insurance history clean.

How Much Should You Trim?

As a general rule, you should hire a reputable tree trimmer.  Keep all tree branches at least 10 feet away from your roofline. This distance creates a buffer zone. It prevents branches from hitting your house during high winds and keeps pests like squirrels and rats from climbing onto your roof.

Let a Local Home Insurance Expert Help You Save

You do not have to shop for coverage completely alone. Reach out to a local independent insurance agent like AlphaSure Affordable Insurance Services. An independent agent can look at multiple home insurance companies at the same time. Thus, they will save you time and help find you the best rates for both your home and car insurance. Call AlphaSure Affordable Insurance Services today to start shopping for car or home insurance tailored perfectly to your budget. You can also go online for free home insurance quote to start the shopping process.

Read More

Home Insurance: The Essential Guide to Protecting Your Home in South Texas

A home covered by home insurance in Laredo TX

For most families living in Texas, a home is more than just a shelter; it is often the single largest financial investment they will ever make. Consequently, understanding the importance of having home insurance is critical for long-term financial stability. While no one expects a disaster, being prepared ensures that a single event doesn’t lead to a total loss of your hard-earned assets.

Homeowners insurance is a contract between you and an insurance provider that provides financial protection against disasters. A standard policy typically covers both damage to the property itself and your legal responsibility for any injuries or property damage you or your family members cause to others.

What Does Home Insurance Cover?

When evaluating policies, many homeowners ask, “What does home insurance cover exactly?” While every policy is unique, most standard homeowners insurance policies include four essential types of coverage:

  • Dwelling Coverage: This pays to repair or rebuild your home if it is damaged by a covered peril such as fire, windstorm, hail, or lightning.
  • Personal Property: Your furniture, clothes, electronics, and other personal items are covered if they are stolen or destroyed by a covered disaster.
  • Liability Protection: This covers you against lawsuits for bodily injury or property damage that family members or pets cause to other people.
  • Additional Living Expenses (ALE): If your home is uninhabitable after a fire or other insured disaster, ALE pays the additional costs of living away from home, such as hotel bills and meals.

However, it is important to note that standard policies in Texas usually do not cover damage caused by floods. Because the weather in South Texas can be unpredictable, discussing these gaps with an independent insurance agent is a vital step in your shopping process.

Why Work with an Independent Insurance Agent?

Choosing the right coverage can be overwhelming. Furthermore, rates can vary significantly between carriers. This is where the value of an independent insurance agent becomes clear. Unlike “captive” agents who work for a single company, an independent agent works for you.

At AlphaSure Affordable Insurance Services, we serve as your starting point in the shopping process. We compare multiple top-rated carriers to find the coverage that fits your specific needs in both San Antonio and Laredo.

Frequently Asked Questions (FAQs)

Read More

Texas Home Insurance Guide: Protect Your Valuables

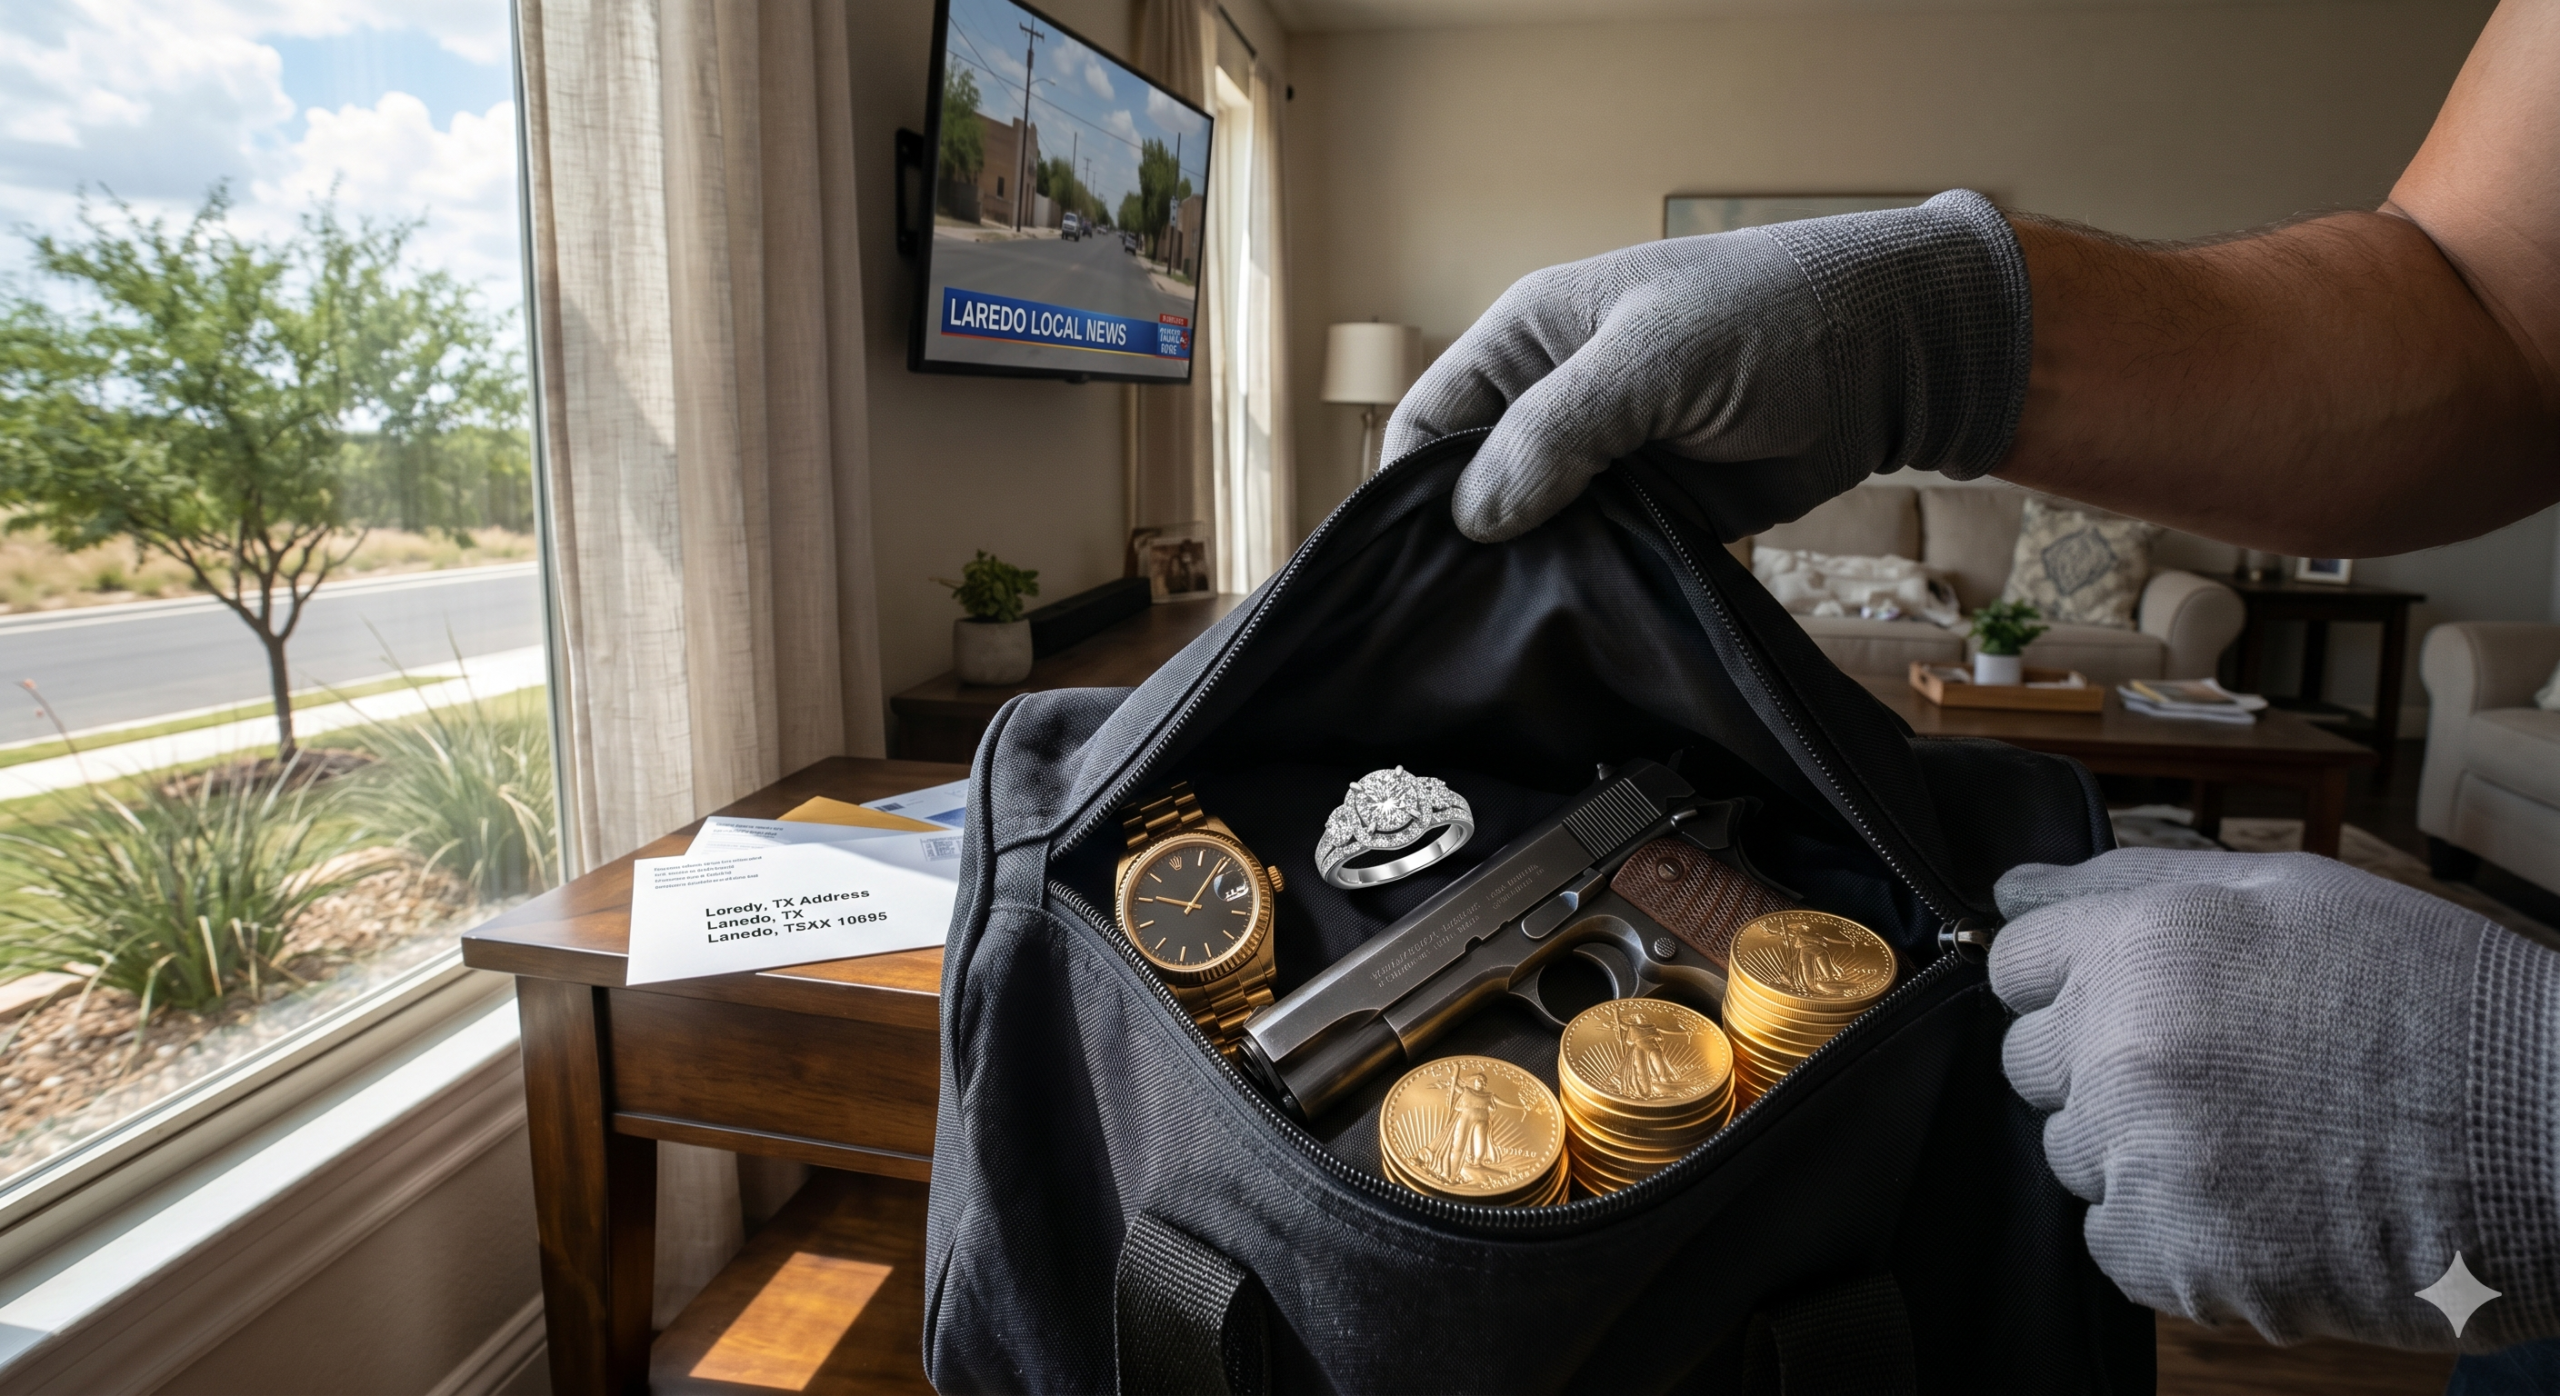
Valuable items being stolen from a home and Home Insurance may not cover these items as you may think

Are you sure your home insurance covers your finest Texas gear? Most homeowners think their policy protects everything inside their house. If a thief breaks in, you expect a check to replace your stolen items. However, many Texans do not know about insurance sublimits. Specific high-value items are not covered the same as, for example, furniture.

What Are Home Insurance Sublimits?

Your policy has a main limit for personal property. This coverage limit is a percentage of the dwelling limit, usually starts at 40%.  However, certain items are covered at a much smaller sublimit. Insurance companies use sublimits to lower their risk on items that thieves steal most often, such as jewelry. If a thief steals your favorite Rolex, a standard home insurance policy might only pay a fraction of its true value.

Four Categories with Low Policy Limits on a Home Insurance Policy

1. Jewelry and Watches Texans love their fine jewelry and bright watches. Sadly, depending on the home insurance policy form, home insurance policies cap the losses by the peril of theft. The sublimit for jewelry to losses by the peril of theft starts at $500!  

2. Firearms Guns are a big part of Texas life and outdoor sports. Yet, most standard policies limit firearm theft coverage to twenty-five hundred dollars. Thus, this small amount barely covers a couple of high-quality rifles or shotguns.

3. Gold, Silver, and Platinum Do you keep precious metals in a home safe? Standard home insurance offers very low protection for precious metals. Most policies cap the losses for precious metals.

4. Fine Arts and Antiques If a thief steals multiple luxury items at once, your payout will be way below the actual value of these high value items. Thus, it is important to properly insure your fine arts and antiques.

How to Protect Your Valuables the Right Way

You do not have to leave your prized items at risk. Instead, you can protect your valuables with two easy choices:

  • Scheduled Personal Property: This adds a specific item to your policy based on its real value. It provides full coverage with no deductible.
  • Insurance Riders: You can buy a policy add-on to raise the sublimit for an entire group, like all your firearms.

Review your home insurance policy today with a local independent insurance agent from AlphaSure Affordable Insurance Services.

Call us today, get a home insurance quote online or visit us at one of our local offices in San Antonio or Laredo, TX.

Read More

Will Home Insurance Cover a New Pool?

There’s nothing more disheartening than realizing there’s so much damage to your pool that you’ll need a new one. However, there are certain situations where home insurance in San Antonio, TX, can help you get a new pool. 

Updated Policy

You need an updated policy when you add amenities to your house, such as a pool. The updated policy will include new coverage limits designed to accommodate the new pool. If you haven’t updated your coverage, the company may deny your claim. 

Covered Events

Homeowners policies only provide coverage for certain events, or "perils." This can include wind damage, fires, vandalism, and various natural disasters. The list of covered perils depends on the company and whether you’ve purchased additional coverage. An agent at AlphaSure Affordable Insurance Services can help you learn what your policy covers. 

Coverage Limits

Every policy has coverage limits, including limits for property damage. If a natural disaster destroys your entire home, pool, and all of your belongings, it’s important to know what your limits are so you can rebuild. A new pool may be more expensive than yours was when you built it. While your insurer may still provide coverage, you may need to prioritize rebuilding your home, and then consider building a pool with the remaining funds. 

We understand the importance of maintaining a gorgeous home, and everyone loves their pool. Several factors influence whether insurance will cover a new pool. Contact an experienced agent at AlphaSure Affordable Insurance Services to learn more about coverage options or what your current policy covers. We’re currently serving the San Antonio, TX, area. 


Read More